
Mammography Detectors Market Size, Share & Demand by 2034
Coverage: By Detector Types (Computed Radiography Detectors, Flat Panel Detectors, CMOS Flat Detectors, Others), End Users (Hospital and Clinics, Diagnostic Centers), and Geography
- Status : Published
- Report Code : TIPRE00025153
- Category : Life Sciences
- No. of Pages : 255
- Available Report Formats :


- Last update date : September 08, 2026


2025 Market Size
US$ 178.49 Mn
Base year value
2034 Forecast
US$ 304.22 Mn
Projected by 2034
CAGR 2026-2034
6.1 %
Growth rate
Addressable Market
US$ 2,185.23 Mn
(2026-2034)
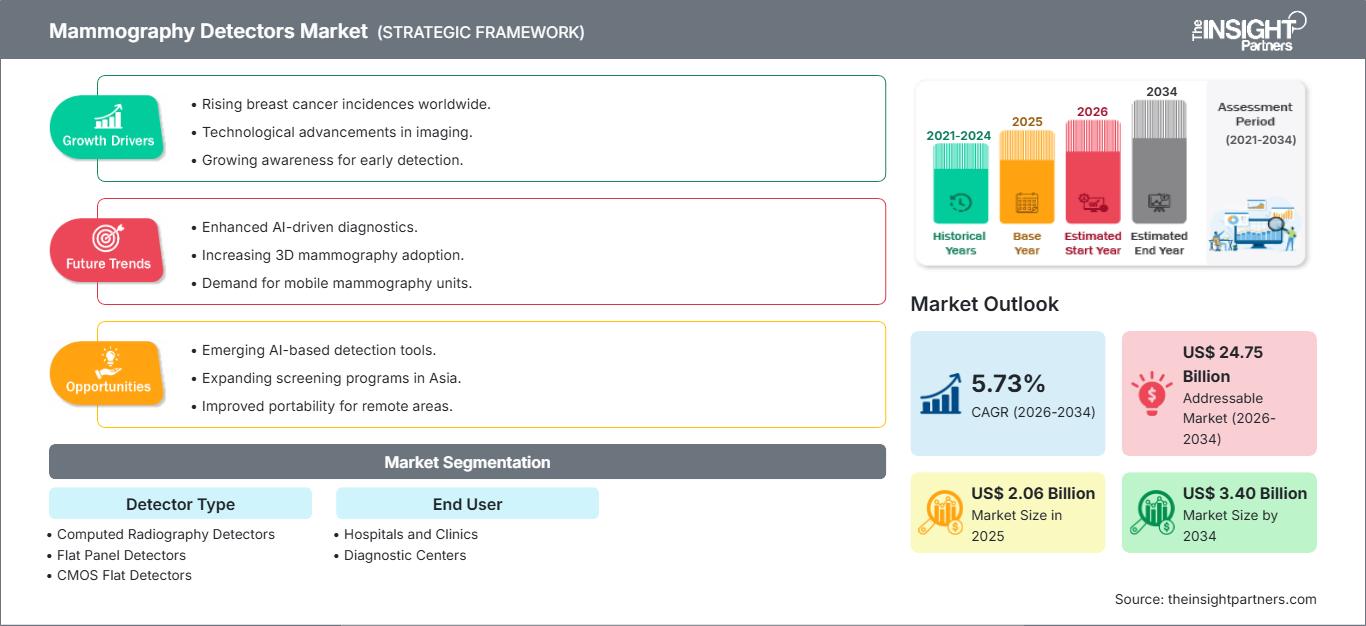
The Mammography Detectors Market was valued at US$ 178.49 million in 2025 and is projected to reach US$ 304.22 million by 2034; it is expected to record a CAGR of 6.1% during 2026–2034. The growth is driven by the adoption of digital breast tomosynthesis technology, image capture system upgrades, and increased need for improved detector sensitivity.
In North America, Mammography Detectors Market size is shaped by organized screening programs, high digital mammography penetration, and steady modernization of breast imaging suites. The region is estimated to expand at a CAGR of 6.0–6.4% during 2026–2034, driven by reimbursement stability, AI imaging workflow solutions, and upgrade opportunities for hospitals and outpatient breast centers.
Mammography Detectors Market Assessment and Insights
- North America The region accounted for 40–42% share in 2025 and is growing at a CAGR between 6.0–6.4% during 2026–2034, supported by strong installed systems, screening adherence, and technology replacement.
- US The US represented 82–86% of North America in 2025 and is growing at a CAGR between 6.1–6.5% during 2026–2034, led by tomosynthesis upgrades.
- Europe Europe held 20–22% share in 2025 and is growing at a CAGR between 5.3–5.7% during 2026–2034, with Germany, the UK, France, Italy, and Spain leading purchasing activity.
- Asia Pacific Asia Pacific captured 26–28% share in 2025 and is growing at a CAGR between 6.7–7.1% during 2026–2034, driven by China, Japan, South Korea, India, and Australia.
- Largest Segment Flat panel detectors held 44–46% market share in 2025, with a CAGR range of 5.1–5.5% during 2026–2034, reflecting broad clinical acceptance.
- High Growth Segment CMOS flat detectors held 24–26% market share in 2025, with a CAGR range of 7.7–8.1% during 2026–2034, supported by compact systems.
- Key companies analyzed in detail: Hologic, Inc.; GE HealthCare Technologies Inc.; Siemens Healthineers AG; Agfa-Gevaert NV; FUJIFILM Holdings Corporation; DRTECH Corporation; Varex Imaging Corporation; Teledyne DALSA, Inc.; Vieworks Co., Ltd.; and Rayence Co., Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The migration of technology involves the shift of breast imaging from analog technology to digitization, reduction of noise and improved resolution. The manufacture of detectors is affected by yield, uniformity in the coating of scintillators, and a longer lifespan within the stringent environment of the health sector. Designers have come up with detector modules that will facilitate tomosynthesis and contrast enhanced mammography.
For the next five years, procurement will increase in underdeveloped regions thanks to the development of public cancer screenings and women's diagnostic services offered by private chains. The regulatory focus on early detection of cancer, optimizing radiation exposure, and software-assisted image analysis increases the need for replacing detectors in the existing base. Investments will most probably be concentrated on CMOS detectors, imaging panels, and service-based detector replacement programs.
Mammography Detectors Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 178.49 Million |
| Market Size by 2034 | US$ 304.22 Million |
| Global CAGR (2026 - 2034) | 6.1% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Mammography Detectors Market Analysis
The prospects for growth in the Mammography Detectors Market are dependent on breast cancer screening rate, detector sensitivity, and economics of replacement. There is increased demand for detection technologies that offer improved resolution while minimizing patient exposure to radiation. Diagnostic centers have increasingly required detectors which enable faster acquisition, reduced re-acquisition rate, and tomosynthesis workstation capability.
Supplier dynamics remain unique because manufacturing of detectors involves advanced electronics, scintillator technology, calibration of panels, and reliable medical grade testing. Original Equipment Manufacturers rely on an ecosystem comprising of experts in detector manufacturing, imaging system manufacturing, software companies, and service providers. These dynamics favour suppliers who are capable of offering production consistency and technical expertise.
The Mammography Detectors Market study reveals a highly competitive market environment comprising vertical integration in imaging firms and detector manufacturers. Hologic, Inc., GE HealthCare Technologies Inc., and Siemens Healthineers AG are competing with full mammography systems, whereas Varex Imaging Corporation, Teledyne DALSA, Inc., Vieworks Co., Ltd., Rayence Co., Ltd., and DRTECH Corporation offer technological advancements on the detector side.
Strategic positioning is now being impacted heavily by AI readiness, tomosynthesis compatibility, life cycle services, and channel access capabilities. FUJIFILM Holdings Corporation and Agfa-Gevaert NV have an advantage due to their imaging workflow solutions, whereas Korean and North American detector companies are competing with CMOS technology and reliability in flat panels. The investment is now focused on manufacturing scalability and detector modules for compact mammography.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Mammography Detectors Market: Strategic Insights
Regional Insights
North America Mammography Detectors Market
North America accounted for 40–42% of Mammography Detectors Market share in 2025 and is expected to grow at a CAGR of 6.0–6.4% during 2026–2034. High screening attendance, established reimbursement routes, and clustering of tomosynthesis systems within the hospitals and ambulatory imaging clinics drive demand. The upgrade of detectors is especially crucial for facilities interested in reducing the exam cycle times.
Adoption of FDA-certified technology, active promotion of women's health programs, and reliable service provided by vendors are the main advantages for the region. Breast imaging centers are upgrading their older digital systems to panels that provide image consistency, effective doses and speed up exam times. Growth of North America is driven by growing popularity of contrast enhanced mammography and artificial intelligence in reading.
U.S. Mammography Detectors Market
The US represented 82–86% of North America in 2025 and is projected to grow at a CAGR of 6.1–6.5% during 2026–2034. The demand of the country depends on dense breast notification, extensive insurance coverage, and constant replacement of installed 2D and early 3D technology. Big companies tend to have detector devices that can operate according to certain standardized protocols.
Presence of the companies is quite important and it includes such firms as Hologic, Inc., GE HealthCare Technologies Inc., Siemens Healthineers AG, Varex Imaging Corporation, and Teledyne DALSA, Inc. The application range grows from standard screenings to diagnostics and biopsies. Purchase considerations include uptime, security of the system, artificial intelligence capability, and cost of ownership.
Europe Mammography Detectors Market
Europe held 20–22% share in 2025 and is expected to expand at a CAGR of 5.3–5.7% during 2026–2034. The UK benefits from structured screening and replacement activity across public imaging networks, although procurement cycles remain budget-sensitive. In terms of demand, reliability, proper dose control and conformity to the national quality standard for breast cancer screenings are key factors.
Germany is the market leader due to its well-developed radiological facilities, strong diagnostics sector and implementation of digital mammography tomosynthesis in specialized centers. France, Italy and Spain are constantly modernizing their capabilities of carrying out screening programs in stages and paying special attention to quality of images and workflow.
APAC Mammography Detectors Market
Asia Pacific accounted for 26–28% share in 2025 and is projected to grow at a CAGR of 6.7–7.1% during 2026–2034. China leads owing to the development of hospitals, manufacture of equipment locally, and also through cancer screening programs. Japan and South Korea facilitate the uptake of high-quality detectors by virtue of their high technology adoption.
India and Australia contribute to the growth of the market due to private diagnostics and cancer screening policies. Industrial factors in the region include manufacture of detectors, semiconductor technologies, and assembly of systems. Value procurement is gaining traction where panels balance quality and affordability.
Middle East & Africa Mammography Detectors Market
Middle East & Africa is expected to grow at a CAGR of 3.6–4.0% during 2026–2034. Saudi Arabia is the leading country, supported by healthcare infrastructure investment and women’s health screening initiatives. While UAE increases its capabilities in premium diagnostics, South Africa is the biggest sub-Saharan country in terms of advanced breast imaging equipment.
Demand in Rest of Middle East & Africa is irregular due to the different level of funding, number of radiologists and service availability. The energy-related investments in hospitals in Gulf states ensure the development of digital radiography units. Yet, the installation of detectors depends on maintenance, training and financing possibilities.
Segmentation Analysis
Detector Types
Detector Types are expected to record a CAGR of 5.8–6.2% during 2026–2034. The Mammography Detectors Market scope across detector technologies is defined by the trade-off between image sensitivity, acquisition time, equipment cost, and clinical workflow. Direct digital and CMOS-based solutions are drawing investment as providers prioritize higher resolution, lower noise, and panel formats suited to tomosynthesis-enabled mammography platforms.
- Computed Radiography Detectors have significance in cost-conscious settings and transitional imaging scenarios that require conversion into digital form but cannot afford high-end digital detectors.
- Flat Panel Detectors are preferred in procurement owing to their assured digital image acquisition capacity, service availability, and compatibility with full-field digital mammography and tomosynthesis systems.
- CMOS Flat Detectors have attained importance strategically because of their fast readout capacity, compact system size, lower power requirements, and application in advanced breast imaging studies.
End Users
End Users are expected to record a CAGR of 5.9–6.3% during 2026–2034. Hospitals and clinics maintain a larger installed base because they manage screening, diagnostic assessment, biopsy support, and multidisciplinary cancer pathways. Diagnostic centers are expanding as outpatient networks scale faster access, but they remain more sensitive to equipment utilization, reimbursement certainty, and capital payback periods.
- Hospital and Clinics are early adopters due to their need for more throughput, more clinical features, and imaging capabilities needed for breast screening, diagnostics, and intervention.
- Diagnostic Centers continue to see strong adoption as the market expands access through the development of outpatient imaging networks, breast screening services and selectively investing in less complex systems.
Opportunity Snapshot
| Segment Name | Revenue Contribution | Trend Tag | Adoption Stage |
| Hospital and Clinics | High | Integrated Care | Mature |
| Diagnostic Centers | Medium | Outpatient Access | Scaling |
Mammography Detectors Market Growth Drivers and Impact Analysis
Rising Breast Cancer Screening Volumes and Earlier Detection Goals
Increased volumes of screening are still the most important structural factor driving detector requirements. Breast cancer has been listed by the World Health Organization as one of the leading types of cancers in women all over the world, putting early detection at the forefront of healthcare planning. Along with increasing screening volumes, radiology departments require detectors which would produce images with consistent quality, short cycle time, and consistency in high-volume conditions. This factor becomes especially apparent in hospitals and diagnostics chains when the old equipment is being replaced in order to provide tomosynthesis, dense breasts diagnosis, and follow up diagnostics.
Shift from Legacy Capture to Direct Digital Imaging Platforms
The change from computed radiography and early digital technologies to advanced flat panel and CMOS detectors is affecting procurement. The latter provide reduced number of procedures, greater availability of images, and quality control processes that surpass those provided by cassettes. In hospitals equipped with several mammography units, it is evident that faster turnaround times and fewer disruptions can be achieved thanks to these advancements. The influence on the market is driven both by replacement as well as upgrades, which involve digital breast tomosynthesis, contrast-enhanced mammography, and artificial intelligence review.
Workflow Pressure from Radiologist Shortages and Higher Exam Complexity
Increasing numbers of imaging studies and limited personnel are two challenges for radiology departments performing breast imaging. Tomosynthesis creates a bigger image database compared to 2D mammography, making speed, consistency of the detector signal, and image quality ready for software processing more relevant. Detectors minimizing the number of retakes and making images easier to reconstruct can help facilities maintain their efficiency while keeping diagnostic criteria unchanged. The second key factor driving procurement is not only the quality but also other features of the detectors that become important for productivity, such as reliability, automation, and compatibility with the PACS system.
Mammography Detectors Market Future Trends
CMOS Integration in Compact and Specialized Breast Imaging Systems
The trends in the market of Mammography Detectors point towards the increasing adoption of CMOS-based detection technologies in small and special purpose breast imaging devices. The CMOS detectors offer fast read-out, low noise electronics, and flexible form-factors, enabling vendors to build systems suitable for small clinics or even outpatient facilities. In the long term, such developments could minimize the reliance on large and expensive machines and enable increased availability of advanced imaging technology. Panel miniaturization, thermal management, and durable electronics are likely to be emphasized by vendors.
Detector Optimization for AI and Contrast-Enhanced Mammography
In future detector development, there will be more emphasis placed on alignment with AI and contrast-enhanced mammography. The success of both of these applications is contingent on having high-quality signal, minimal artifacts, and calibration that can be relied upon, because the image itself is a necessary input into the algorithm. Detectors may increasingly collaborate with the system OEMs and software providers to ensure that the data obtained by the detector can be used for automated lesion detection, density analysis, and image reconstruction.
Mammography Detectors Market Opportunities
Replacement Programs for Aging Digital Mammography Installations
Demand from replacements provides an actual possibility for suppliers addressing hospitals, clinics, and imaging chains with old mammography systems. There is a lot of installed equipment which is still effective in use, but is limited in such aspects as efficiency of detectors, maintenance, and software compatibility. Suppliers can take advantage of that by providing customers with possibilities of upgrading, detector replacement along with maintenance services and financing solutions that would lower the cost of purchasing Forecast for Mammography Detectors Market indicates increasing demand in places where facilities can enhance their workflow without changing the room.
Emerging Market Access Through Value-Based Detector Platforms
The developing market has potential for detectors built on a platform of cost, longevity, and simplicity of service. In many areas, the need for screening is growing more quickly than funds available for high-end technology, thus providing room for affordable digital mammography devices. It is in the interests of vendors to enter into joint ventures with local distributors, public hospitals, and privately owned diagnostic networks for the supply of appropriate detectors. Successful implementation of such plans will require proper compromise between imaging performance, ease of service, and regulatory approvals.
Recent Developments
- June 2026: In a positive development for Hologic, the company received an IP win against Siemens Healthineers in an adverse patent decision against the latter firm by the Unified Patent Court (UPC). This court ruling was in favor of Hologic because Siemens’ MAMMOMAT B.brilliant mammography systems violated the Focusing Technology patented by Hologic under European Patent EP 2 352 431 in its Envision™ system.
- June 2026: Installation of the First AI Digital Mammography System by FUJIFILM India at NM Medical, India. The AMULET SOPHINITY system by FUJIFILM uses artificial intelligence technology along with low-dose mammography for effective visualization and diagnosis. This installation is a step forward towards providing women's health care services using advanced and precision-based breast imaging technology.
- April 2026: GE HealthCare also announced an extended partnership with DeepHealth, Inc., which is a worldwide expert on AI-based health informatics and a subsidiary of RadNet, Inc., for further development and promotion of mammography solutions based on artificial intelligence technology. This news came at the time of SBI Annual Symposium, where GE HealthCare is presenting its newest developments in breast imaging and women’s health.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for