
Rectifier Diode Market Demand, Trends & Forecast by 2034
Coverage: by Type (Standard Diodes, Fast Recovery Diodes, Schottky Diodes, Zener Diodes, Others); Material (Silicon Carbide, Gallium Nitride); Application (Automotive, Consumer Electronic, Household Appliances, Industrial, Others); and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPTE100000429
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 16, 2026


2025 Market Size
US$ 4.57 Bn
Base year value
2034 Forecast
US$ 7.53 Bn
Projected by 2034
CAGR 2026-2034
5.70 %
Growth rate
Addressable Market
US$ 54.82 Bn
(2026-2034)
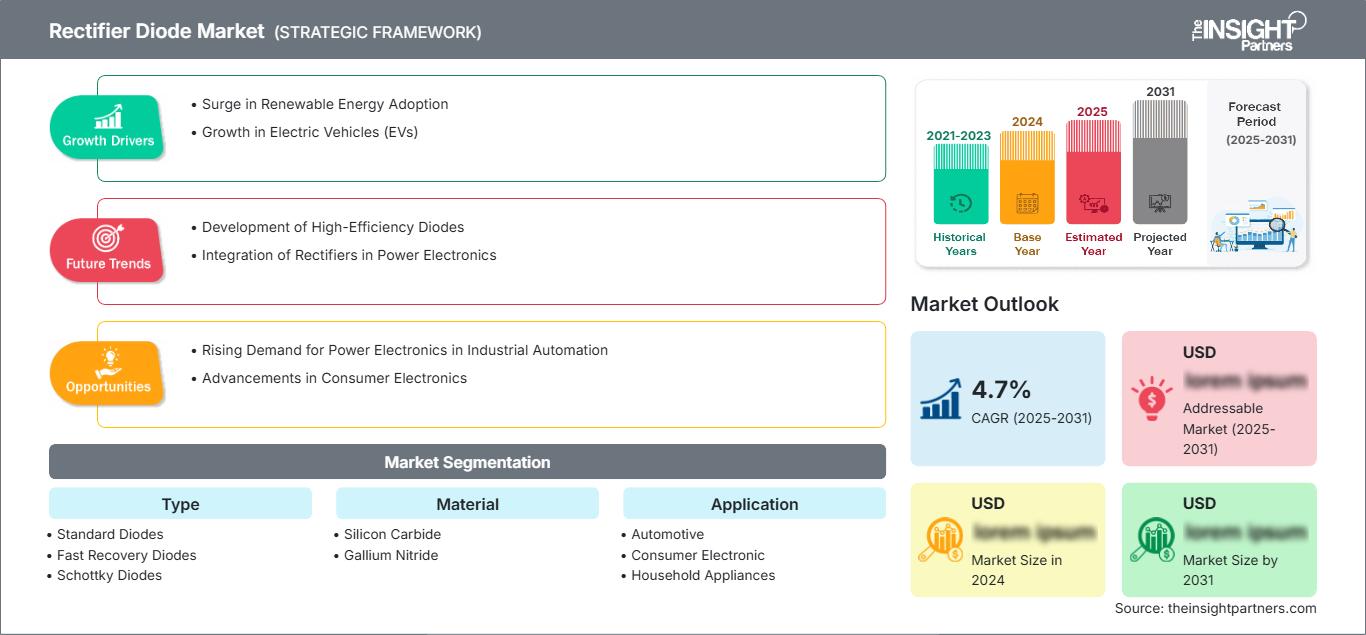
The rectifier diode market was valued at US$ 4.57 Billion in 2025 and is projected to reach US$ 7.53 Billion by 2034, registering a CAGR of 5.70% from 2026 to 2034. The expansion reflects continued demand for efficient AC-to-DC conversion across automotive electronics, consumer devices, appliances, industrial equipment, and power-management systems. Increasing electrification and higher efficiency requirements are also supporting adoption of advanced rectification technologies across multiple voltage and power classes.
North America is expected to maintain a substantial position in the Rectifier Diode Market Share, supported by semiconductor manufacturing investment, data-center power infrastructure, automotive electrification, and industrial automation. The region is estimated to expand at a 6.0–6.6% CAGR between 2026–2034, while demand for higher-efficiency power conversion increasingly favors advanced diode architectures and wide-bandgap materials.
Rectifier Diode Market Assessment and Insights
- North America: The region is estimated to account for 34–38% share in 2025 and grow at a 6.0–6.6% CAGR between 2026–2034, supported by semiconductor investment, automotive electrification, data-center infrastructure, and industrial power conversion.
- US: The US represents approximately 80–84% of North American demand in 2025 and is projected to expand at a 6.1–6.7% CAGR between 2026–2034, supported by advanced electronics manufacturing and electrification investment.
- Europe: Europe is estimated to hold 21–25% share in 2025 and expand at a 5.4–6.0% CAGR between 2026–2034, led by Germany, the UK, France, Italy, and Spain, with automotive and industrial power electronics supporting demand.
- Asia Pacific: Asia Pacific is estimated at 39–43% share in 2025 and projected to grow at a 6.2–7.0% CAGR between 2026–2034, led by China, Japan, South Korea, India, and Australia.
- Largest Segment: Standard Diodes hold an estimated 39–43% market share in 2025, expanding at a 4.8–5.5% CAGR between 2026–2034, supported by broad-volume electronic applications.
- High Growth Segment: Silicon Carbide is projected to record a 9.0–10.0% CAGR between 2026–2034, driven by high-efficiency automotive, renewable-energy, charging, and industrial power-conversion applications.
- Key companies analyzed in detail: Fairchild Semiconductor International, Inc.; Infineon Technologies AG; NXP Semiconductors N.V.; onsemi; PANJIT International Inc.; Renesas Electronics Corporation; ROHM Co., Ltd.; STMicroelectronics N.V.; Toshiba Corporation; Vishay Intertechnology, Inc.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The industry is moving from traditional silicon rectification to higher-speed switching devices, low forward voltage Schottky devices, and wide bandgap rectifiers. Production is still being done by companies that have capabilities in wafer fabrication, packaging, and distribution of semiconductors. For instance, Infineon has rectifier diodes that range from 400 V to 9,000 V and currents from 120 A to 8,400 A.
In the future, investments will be made in SiC and GaN production, automotive-grade qualifications, smaller packaging, and higher frequency power conversion. China, India, Southeast Asia, and many other manufacturing countries in Asia will gain capacity as electronics and electric vehicle supply chains expand. Regulatory push for energy efficiency and industrial decarbonization will drive more rectifiers.
Rectifier Diode Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 4.57 Billion |
| Market Size by 2034 | US$ 7.53 Billion |
| Global CAGR (2026 - 2034) | 5.70% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Rectifier Diode Market Analysis
Demand is sustained by the need to convert and regulate electrical energy efficiently across power supplies, chargers, motor drives, consumer electronics, appliances, and vehicle electrical systems. The rectifier diode market growth ecosystem includes wafer producers, diode manufacturers, packaging specialists, distributors, OEMs, automotive suppliers, industrial-equipment companies, and power-system integrators. Standard silicon products remain essential where cost and proven reliability dominate selection.
In terms of technology, supply is moving towards different types of equipment that can have greater voltage capability, low conduction losses, fast switching and better thermal properties. Silicon carbide Schottky diodes, in particular, are well-suited for high-frequency rectification due to their relatively stable switching characteristics at high temperatures. As per ROHM, its SiC SBDs are employed in battery chargers, xEV charger circuits, solar cells, and power factor correction systems.
Competitive intensity is shaped by manufacturing scale, automotive qualification, product breadth, wafer technology, packaging expertise, and regional supply availability in the Rectifier Diode Market Report. Infineon Technologies AG maintains high-power rectifier portfolios, while Vishay Intertechnology, Inc., onsemi, NXP Semiconductors N.V., Renesas Electronics Corporation, and STMicroelectronics N.V. address automotive, industrial, and consumer applications. ROHM Co., Ltd. differentiates through SiC SBD technology and compact high-voltage packages.
Strategic investment is increasingly focused on wide-bandgap capacity, advanced packaging, and application-specific products. STMicroelectronics N.V. is expanding SiC manufacturing capacity, including a 200 mm facility in Italy targeted for production from 2026, while its China manufacturing initiative supports regional automotive and industrial demand. Such investments strengthen supply-chain control and enable higher-volume production of advanced power devices.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Rectifier Diode Market: Strategic Insights
Regional Insights
North America rectifier diode market
North America is estimated to represent 34–38% of the rectifier diode Market share in 2025 and is projected to grow at a 6.0–6.6% CAGR between 2026–2034. The growth in semiconductor production, automotive electric vehicles, renewable energy projects, data centers, and automation will contribute to this region. Incentives in semiconductors from the US, as well as spending on grid modernization, have also been helping in driving demand for power management components.
Regional sourcing includes both global players and players specialized in power semiconductors. Increasing demand is coming from automotive and industrial end-users who are looking for power components with increased switching speeds and energy efficiency. Data centers will provide yet another application avenue for power semiconductor components since power conversion structures will have to handle increasing density and efficiency challenges.
U.S. rectifier diode Market
The US represents approximately 80–84% of North American rectifier diode Market demand in 2025 and is expected to grow at a 6.1–6.7% CAGR between 2026–2034. The demand driver is the domestic investment in semiconductors, production of EVs, renewable energy projects, industrial automation, aerospace applications, and hyperscale data centers.
Some of the international companies that have significant product presence include Infineon Technologies AG, onsemi, Vishay Intertechnology, Inc., NXP Semiconductors N.V., etc. The application demands are increasingly becoming more stringent and are moving towards automotive-level ruggedness, small-size power solutions, efficient charging infrastructure, and data center power conversions.
Europe rectifier diode Market
Europe is estimated to hold 21–25% share of the rectifier diode Market in 2025 and is projected to grow at a 5.4–6.0% CAGR between 2026–2034. Germany remains the leading national market, supported by automotive manufacturing, industrial automation, renewable-energy integration, and power-electronics engineering.
The UK has strong demand from data centers, renewable generation, industrial equipment, and advanced electronics. Germany benefits from its automotive and industrial manufacturing base, where efficient power conversion is increasingly important for EVs, factory automation, and energy-management systems. France, Italy, and Spain contribute through transportation electrification, industrial modernization, renewable projects, and consumer-electronics manufacturing. European procurement increasingly emphasizes efficiency, reliability, automotive qualification, and supply-chain resilience.
APAC rectifier diode Market
APAC represents an estimated 39–43% share of the rectifier diode Market in 2025 and is expected to expand at a 6.2–7.0% CAGR between 2026–2034. China remains the leading market because of its extensive electronics manufacturing, EV production, renewable-energy deployment, and semiconductor ecosystem.
Japan and South Korea contribute through advanced automotive and electronics manufacturing, while India is expanding demand through electrification, consumer electronics, appliances, and industrial modernization. Australia provides opportunities in renewable-energy conversion and grid-related power electronics. The region's large manufacturing base, expanding domestic consumption, and increasing investment in advanced semiconductor production should preserve its leading position.
Middle East & Africa rectifier diode Market
Middle East and Africa rectifier diode Market demand is supported by infrastructure development, renewable-energy projects, industrialization, and increasing investment in reliable electricity systems. Saudi Arabia is expected to lead regional demand, followed by the UAE and South Africa, while the rest of MEA provides opportunities through electrification and energy projects.
The region is projected to expand at a 5.0–5.8% CAGR between 2026–2034. Saudi Arabia and the UAE are developing large-scale energy and infrastructure projects requiring power-conversion equipment, while South Africa provides demand from industrial systems and renewable installations. Localized distribution and technical-support capabilities remain important for suppliers entering less mature markets.
Segmentation Analysis
Type
Type remains a central determinant of device selection because different rectifier architectures balance forward voltage, reverse recovery, switching speed, leakage, voltage rating, and cost. Standard products retain high-volume applications, while fast recovery and Schottky structures address increasingly demanding switching environments. The segment is projected to expand at a 5.0–5.7% CAGR between 2026–2034 in the Rectifier Diode Market Forecast.
- Standard Diodes: Standard Diodes serve broad rectification requirements across power supplies, appliances, industrial equipment, and general electronics where proven performance, availability, and cost efficiency remain important purchasing considerations.
- Fast Recovery Diodes: Fast Recovery Diodes support high-frequency switching circuits by reducing reverse-recovery losses, making them important in motor drives, converters, power supplies, and industrial switching equipment.
- Schottky Diodes: Schottky Diodes provide low forward voltage and fast switching, supporting compact power supplies, automotive electronics, chargers, and other applications where conversion efficiency and thermal performance are critical.
- Zener Diodes: Zener Diodes are primarily used for voltage regulation, clamping, and protection functions, complementing rectification circuits in consumer, automotive, industrial, and electronic control systems.
Material
Material selection is increasingly influenced by operating voltage, switching frequency, thermal environment, efficiency targets, and system cost. Silicon remains fundamental to high-volume applications, while wide-bandgap materials increasingly address demanding power-conversion requirements. The material segment is projected to expand at a 7.5–8.5% CAGR between 2026–2034, reflecting key Rectifier Diode Market Trends.
- Silicon Carbide: Silicon Carbide supports high-voltage and high-temperature applications requiring low losses and fast switching, particularly EV chargers, solar inverters, industrial converters, and renewable-energy systems.
- Gallium Nitride: Gallium Nitride is strategically important for high-frequency power conversion because of its switching performance, compact device potential, and suitability for chargers, adapters, data-center power systems, and emerging high-density architectures.
Application
Application demand spans high-volume consumer equipment and increasingly sophisticated automotive and industrial power-conversion systems in the Rectifier Diode Market. Electrification is expanding the number of conversion stages requiring efficient rectification, while industrial customers emphasize thermal performance and reliability. The application segment is projected to grow at a 5.5–6.2% CAGR between 2026–2034.
- Automotive: Automotive applications increasingly use rectification devices in onboard chargers, DC-DC converters, auxiliary systems, lighting, and electrified powertrains, raising requirements for efficiency, thermal stability, reliability, and qualification.
- Consumer Electronic: Consumer Electronics equipment requires compact and efficient rectification in adapters, chargers, televisions, computing products, and connected devices, with high-volume production reinforcing cost and package optimization.
- Household Appliances: Household Appliances use rectification devices in motor controls, power supplies, HVAC systems, refrigerators, washing machines, and other electronically controlled equipment where efficiency and dependable operation are essential.
- Industrial: Industrial applications include motor drives, UPS systems, power supplies, renewable-energy converters, and battery chargers, creating demand for higher-voltage, high-current, thermally robust rectifier technologies.
Opportunity Snapshot
| Application | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
| Automotive | High | EV Charging | Scaling |
| Consumer Electronic | High | Compact Power | Mature |
| Household Appliances | Medium | Motor Control | Mature |
| Industrial | High | Power Conversion | Scaling |
Rectifier Diode Market Growth Drivers and Impact Analysis
Vehicle Electrification Expands High-Efficiency Power Conversion
Increased use of power conversion stages is being witnessed due to vehicle electrification in both passenger cars and commercial vehicles. These include onboard chargers, DC-DC converters, auxiliary power systems, battery management systems, and traction electronics that will demand the use of semiconductor devices capable of working efficiently in challenging thermal and electrical environments. For designs requiring lower switching losses and high power densities, SiC products stand out as the best solution. The SiC Schottky Barrier Diodes from ROHM are identified for use in battery chargers and charging circuits of electric or hybrid vehicles. STMicroelectronics has developed SiC semiconductors for automotive power systems. The market impact is not only based on individual shipments since product development, qualification, and long-term designs in the automotive industry are increasing.
Industrial Energy Efficiency Raises Demand for Advanced Rectifiers
The industry sector is investing more in efficient motor drives, UPS solutions, energy converter systems, battery charger modules, and power supply systems to cut back on electricity usage and enhance equipment efficiency. Rectifiers play an important role in such power conversion systems, and the demand for their efficiency is rising owing to the growing density of operation of industrial equipment. Infineon Technologies AG lists among the major applications that include motor control, power supply systems, battery chargers, electrolysis, traction, and wind power generation for its line of rectifiers. The wide range of applications makes silicon-based products highly demanded, alongside some incremental demands for SiC-based products. It is because the demand for rectifiers is affected by the continuous operation of equipment or equipment operating in a high-temperature environment.
Data-Center Power Density Creates New Conversion Requirements
The fast rise of AI computing is affecting the power distribution needs in data centers and thereby paving the way for semiconductor technologies that can handle higher voltage, power density, and conversion efficiency. STMicroelectronics unveiled an 800 VDC power distribution scheme in 2025 that used a combination of silicon, SiC, and GaN technologies, including a 12 kW GaN converter running at 1 MHz with efficiency exceeding 98%. Even though next-generation designs are helping to eliminate some of the need for conventional rectification stages in certain topologies, they are, at the same time, raising the demand for high-performance power semiconductors in other parts of the conversion process. The end result is an industry trend towards the use of high-frequency products, smaller form factors, and semiconductor materials that can withstand harsh electrical and thermal conditions. This presents opportunities for rectifiers in high-density server power supplies, battery backup systems, solar-powered data centers, and distributed architectures.
Rectifier Diode Market Future Trends
Wide-Bandgap Devices Move Toward Broader Commercial Adoption
With growing capacity and increased focus from system designers on efficiency, switching frequency, and compactness, both SiC and GaN technologies are anticipated to evolve out of their niche markets. While SiC Schottky diodes have enabled high-voltage charging and renewable energy applications, GaN is emerging as the material of choice for high-frequency power conversion. During the forecast period, semiconductor manufacturers will strive to enhance wafer yield, packaging, qualification, and performance optimization for particular applications to bridge the pricing difference compared to silicon technologies. With more customers in the automotive, industrial, and data center segments looking to make system-based decisions in selecting semiconductors based on conversion losses and cooling needs, not just pricing, a differentiated market would emerge where silicon dominates low-cost applications while wide bandgap devices target high-value opportunities.
Advanced Packaging Becomes a Performance Differentiator
Packaging is expected to become increasingly important as rectification devices operate at higher power densities and tighter thermal limits. Surface-mount formats, improved creepage distances, enhanced heat dissipation, and compact electrical layouts can allow designers to reduce system size while maintaining safety and reliability. ROHM's SiC SBD portfolio demonstrates this direction, including compact packages designed for high-voltage applications and improved insulation performance. Future products are likely to combine optimized die structures with advanced thermal interfaces and package geometries tailored to automotive, industrial, and high-density computing environments. Packaging innovation can also simplify automated assembly and enable drop-in replacement of conventional components, increasing adoption among OEMs. Suppliers that combine semiconductor performance with manufacturing-friendly packaging should gain stronger design-in positions as system architectures become more compact and thermally constrained.
Rectifier Diode Market Opportunities
SiC Supply-Chain Expansion for Automotive and Energy Applications
Investment opportunities are emerging around vertically integrated SiC supply chains covering substrates, wafers, device fabrication, packaging, and testing. Automotive electrification and renewable-energy conversion provide long-term demand for high-voltage devices, while manufacturers increasingly seek secure supply and consistent quality. STMicroelectronics is developing a 200 mm SiC manufacturing campus in Italy, targeted to begin production in 2026 and ultimately reach substantial weekly wafer capacity. Similar investments across Asia and other regions can expand availability and improve manufacturing economics. Suppliers and investors can prioritize capacity serving 650 V to 1,200 V applications, automotive-qualified products, and industrial converters. Strategic partnerships with vehicle manufacturers, charger producers, and inverter suppliers can further improve utilization because design-ins establish longer product lifecycles and reduce dependence on spot-market semiconductor demand.
Localized Semiconductor Manufacturing in Asia
Asia provides a significant opportunity for manufacturers seeking proximity to electronics, automotive, renewable-energy, and appliance customers. China, Japan, South Korea, and India combine large end markets with established component ecosystems, while regional governments continue encouraging semiconductor manufacturing and supply-chain localization. STMicroelectronics and Sanan Optoelectronics established a China-focused SiC manufacturing initiative designed to support automotive and industrial customers, illustrating the strategic importance of localized power-semiconductor capacity. Suppliers can pursue opportunities through local wafer production, packaging partnerships, application-engineering centers, and distributor networks. Localization can shorten lead times, reduce supply-chain exposure, and improve responsiveness to OEM qualification requirements. The opportunity is strongest for companies that combine competitive manufacturing economics with application-specific engineering and reliable regional technical support.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for