
Non-Volatile Memory Market Trends, Size & Forecast by 2034
Coverage: by Type (Flash Memory, EPROM, nvSRAM, EEPROM, 3D NAND, MRAM, FRAM, NRAM, ReRAM, PMC); Wafer Size (200 mm, 300mm); End-user (Consumer Electronics, Enterprise Storage, Healthcare, Automotive), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPEL00002041
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 15, 2026


2025 Market Size
US$ 88.09 Bn
Base year value
2034 Forecast
US$ 200.37 Bn
Projected by 2034
CAGR 2026-2034
9.56 %
Growth rate
Addressable Market
US$ 1,286.56 Bn
(2026-2034)
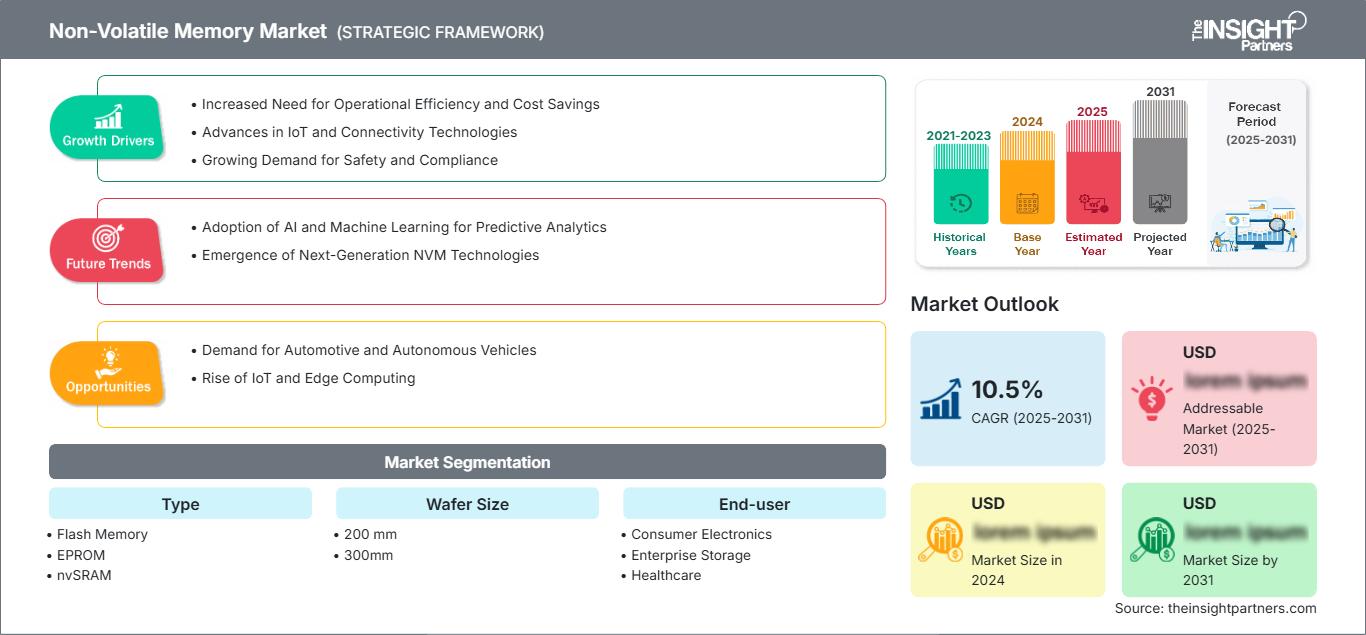
The non-volatile memory market was valued at US$ 88.09 Billion in 2025 and is projected to reach US$ 200.37 Billion by 2034, registering a CAGR of 9.56% during 2026–2034. The market continues to evolve as data-intensive computing, connected devices, automotive electronics, and enterprise digital infrastructure increase demand for persistent memory technologies offering higher storage density, lower power consumption, faster access speeds, and improved endurance across diverse industrial and consumer applications.
Growing investments in semiconductor manufacturing and advanced packaging continue to reinforce North America's strategic position within the global ecosystem. The region benefits from strong research capabilities, a robust fabless semiconductor industry, expanding cloud infrastructure, and increasing deployment of artificial intelligence hardware. The non-volatile memory market size across North America is supported by sustained innovation in enterprise storage, automotive electronics, and defense applications, with the regional market expected to expand at a CAGR ranging between 8.8% and 9.4% through the forecast period.
Non-Volatile Memory Market Assessment and Insights
- North America: The region maintains technological leadership through advanced semiconductor design, hyperscale data center investments, and strong enterprise storage demand. Share in 2025: 30–34%. CAGR between 2026–2034: 8.8–9.4%.
- US: The country remains the regional innovation hub, supported by leading semiconductor manufacturers, cloud service providers, and defense electronics investments. Share in 2025: 78–82% of North America. CAGR between 2026–2034: 8.9–9.5%.
- Europe: Supported by automotive electronics, industrial automation, and semiconductor policy initiatives, Europe demonstrates stable expansion led by Germany, France, the United Kingdom, and Italy. Share in 2025: 20–24%. CAGR between 2026–2034: 8.3–8.9%.
- Asia Pacific: The region represents the largest manufacturing and consumption base, driven by China, Japan, South Korea, Taiwan, and India, supported by expanding electronics production and semiconductor investments. Share in 2025: 40–45%. CAGR between 2026–2034: 10.4–11.0%.
- Largest Segment: Flash Memory remains the leading segment owing to widespread deployment across smartphones, solid-state drives, embedded systems, and consumer electronics. Market share in 2025: 42–47%. CAGR between 2026–2034: 9.2–9.8%.
- High Growth Segment: 3D NAND is projected to witness the fastest expansion as manufacturers increase layer counts to improve storage density and reduce cost per bit. Market share in 2025: 17–21%. CAGR between 2026–2034: 12.0–12.8%.
- Key companies analyzed in detail: Samsung Electronics Co., Ltd.; Western Digital Technologies, Inc.; KIOXIA Holdings Corporation; Micron Technology, Inc.; SK hynix Inc.; Microchip Technology Incorporated; ROHM Co., Ltd.; Renesas Electronics Corporation; STMicroelectronics N.V.; Infineon Technologies AG.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Semiconductor fabrication technologies, memory stack design, and storage interface innovations have fundamentally changed the environment in which persistent memory technologies compete. The increasing use of AI-driven workloads, cloud-native applications, connected cars, automation, and edge computing keeps boosting the demand for dense and low-latency memory devices. Semiconductor manufacturers are scaling up wafer manufacturing processes, reducing the size of process nodes, and implementing vertically integrated supply chains to increase the yield of their products, optimize production costs, and reduce the vulnerability of production facilities to geopolitical risks and raw material availability.
The development of new controller designs and memory package technologies will further improve performance, endurance, and energy efficiency. Future trends include an increase in investment activity in newly established semiconductor manufacturing regions in Asia Pacific, North America, and some European countries based on government initiatives to invest in local chip manufacturing. Software-defined infrastructures, next-generation cars, healthcare systems, and IoT applications will drive the demand for the newest generation of memory devices. Government interest in supply chain resilience, technology independence, and energy-efficient semiconductor manufacturing is expected to drive investments and collaborations towards the development and manufacturing of future non-volatile memory devices.
Non-Volatile Memory Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 88.09 Billion |
| Market Size by 2034 | US$ 200.37 Billion |
| Global CAGR (2026 - 2034) | 9.56% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Non-Volatile Memory Market Analysis
Persistent demand for digital storage across consumer electronics, enterprise infrastructure, automotive electronics, and industrial automation continues to strengthen the non-volatile memory market growth trajectory. Increasing data generation from artificial intelligence, edge computing, fifth-generation communication networks, and connected devices requires memory solutions capable of delivering faster read-write performance, high endurance, and lower power consumption. On the other hand, value chain integration is also becoming more evident in the industry with the collaboration between semiconductor firms and equipment providers, wafer producers, controller designers, and cloud computing companies aimed at boosting the efficiency of production and quicker commercialization of innovative memory architectures.
The supply side factors are driven by investments in 300mm wafer manufacturing, advanced packaging techniques and process improvements allowing higher yields and lower cost per bit. The development and adoption of multi-layered memory structures continue together with geographical diversification of the manufacturing sites as protection against potential disruptions in the supply chain. This allows wider usage of the technology for enterprise storage, automotive safety, healthcare devices, and industrial equipment.
The non-volatile memory market analysis indicates a highly competitive environment where established semiconductor manufacturers differentiate through process technology, intellectual property portfolios, manufacturing scale, and long-term customer relationships. Samsung Electronics Co., Ltd., SK hynix Inc., Micron Technology, Inc., KIOXIA Holdings Corporation, and Western Digital Technologies, Inc. continue investing in higher-layer NAND technologies, advanced controllers, and next-generation storage platforms. Meanwhile, STMicroelectronics N.V., Infineon Technologies AG, Renesas Electronics Corporation, ROHM Co., Ltd., and Microchip Technology Incorporated strengthen their positions in embedded and automotive applications through specialized non-volatile memory portfolios.
Capital allocation becomes more inclined towards increasing fabrication capabilities, enhancing the manufacturing process, and speeding up the research in novel memory devices like MRAM, ReRAM, and Ferroelectric memories. Collaborative efforts from the semiconductor companies, automobile companies, cloud infrastructural companies, and research organizations help in innovation as well as in cutting down the commercialization period. The competitive position is also affected by localizing supply chains, sustainability goals, and investing in innovative semiconductor ecosystems to cater to changing customer needs in high-performance computing, industrial electronics, medical electronics, and advanced mobility solutions.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Non-Volatile Memory Market: Strategic Insights
Regional Insights
North America Non-volatile Memory Market
North America accounted for an estimated 30–34% share of the global market in 2025 and is projected to expand at a CAGR of 8.8–9.4% through 2034. The non-volatile memory market share in the region is supported by extensive investments in cloud computing infrastructure, artificial intelligence accelerators, high-performance enterprise storage, and advanced automotive electronics. Sustained competitiveness of the region is further aided by the government’s support for manufacturing semiconductors and investments made in the development of facilities that manufacture semiconductor chips.
The presence of key semiconductor design companies, memory production firms, hyperscale cloud computing providers and research organizations accelerates the development and commercialization of the emerging storage technologies. Defense electronics, industrial automation, healthcare devices and mobility applications fuel the steady growth. Investments in advanced packaging, wafer fabrication and semiconductor research will ensure that North America acts as an innovation hub for high-performance non-volatile memory technologies.
U.S. Non-volatile Memory Market
The United States represented approximately 78–82% of the North American Non-volatile Memory Market in 2025 and is anticipated to register a CAGR of 8.9–9.5% during the forecast period. Wide use of enterprise storage, AI infrastructure, aerospace systems, defense electronics, and automotive technologies has kept boosting the domestic demand. Government policies that encourage the manufacture of semiconductors and the associated research have also led to increased investments in the fabrication capabilities of the industry.
It is home to many semiconductor pioneers such as Micron Technology, Microchip Technology Incorporated, Western Digital Technologies, Inc., and other design centers around the world for memory development. Increasing use of data centers, software-defined infrastructure, medical electronics, and IoT industrial platforms is driving up the need for higher-capacity, energy-efficient storage solutions. Constant innovation in controller technology and memory architecture is helping ensure sustainable market growth in the country.
Europe Non-volatile Memory Market
Europe captured an estimated 20–24% share of the global Non-volatile Memory Market in 2025 and is forecast to grow at a CAGR of 8.3–8.9% through 2034. Regional demand is driven by automotive electrification, industrial automation, smart manufacturing, and expanding investments in semiconductor sovereignty. Germany remains the leading contributor owing to its strong automotive supply chain, advanced industrial manufacturing base, and continuous investments in semiconductor research and production capacity.
The United Kingdom continues to strengthen its position through semiconductor design expertise, artificial intelligence development, and university-led research collaborations supporting emerging memory technologies. France, Italy, and Spain collectively contribute through expanding automotive electronics, aerospace manufacturing, industrial automation, and digital healthcare initiatives. The presence of companies such as STMicroelectronics N.V. and Infineon Technologies AG further enhances regional innovation while supporting adoption across industrial, consumer, and mobility applications.
APAC Non-volatile Memory Market
Asia Pacific represented approximately 40–45% of global Non-volatile Memory Market demand in 2025 and is expected to record the fastest regional expansion with a CAGR of 10.4–11.0%. China, Japan, South Korea, India, and Australia continue strengthening semiconductor manufacturing ecosystems through public investment, private capital expenditure, and expanding electronics production.
China remains the largest regional market, while South Korea and Japan lead advanced memory manufacturing and technology innovation. India is emerging as a strategic semiconductor destination through policy incentives and electronics manufacturing expansion, supporting sustained regional demand across consumer electronics, automotive systems, cloud infrastructure, and industrial automation.
Middle East & Africa Non-volatile Memory Market
The Middle East & Africa Non-volatile Memory Market is projected to expand at a CAGR of 7.2–7.8% during the forecast period. Increasing digital transformation initiatives, smart city investments, telecommunications modernization, and industrial automation projects are supporting gradual adoption across Saudi Arabia, the United Arab Emirates, South Africa, and the rest of the region.
Saudi Arabia and the United Arab Emirates continue investing in digital infrastructure, hyperscale data centers, and artificial intelligence applications, while South Africa remains an important technology adoption market. Expanding energy, transportation, healthcare, and public infrastructure modernization programs are expected to create long-term opportunities for advanced non-volatile memory deployment across diverse industrial sectors.
Segmentation Analysis
Type
The Type segment represents the core technology foundation of the industry and is projected to grow at a CAGR of 9.8–10.4% during 2026–2034. Technology selection is influenced by endurance, write speed, retention capability, power efficiency, and application-specific performance requirements. The non-volatile memory market scope continues to expand as manufacturers commercialize advanced memory architectures for artificial intelligence, automotive electronics, industrial automation, and enterprise storage while improving scalability and manufacturing efficiency.
- Flash Memory: Continues to dominate due to extensive deployment in smartphones, solid-state drives, embedded systems, and consumer electronics. Its balance of storage density, reliability, and cost efficiency supports widespread adoption across both consumer and enterprise environments.
- EPROM: Maintains relevance in industrial control systems, legacy embedded electronics, and specialized programmable applications where occasional firmware updates and dependable long-term data retention remain operational priorities.
- nvSRAM: Serves mission-critical networking, telecommunications, aerospace, and industrial automation applications by combining SRAM performance with persistent data storage during unexpected power interruptions.
- EEPROM: Remains widely utilized in automotive electronics, smart meters, healthcare devices, and embedded controllers because of its flexibility for selective byte-level rewriting and dependable long-term data storage.
- 3D NAND: Gains significant traction through higher storage density, improved scalability, and lower cost per bit, making it increasingly important for enterprise solid-state drives, cloud infrastructure, and advanced consumer devices.
- MRAM: Experiences increasing deployment across industrial automation, automotive safety systems, and edge computing platforms due to high endurance, rapid switching capability, and excellent resistance to harsh operating environments.
- FRAM: Finds growing applications in smart cards, healthcare monitoring equipment, industrial sensors, and low-power embedded electronics where fast write performance and minimal energy consumption are essential.
- NRAM: Attracts research and commercialization interest for future high-performance computing applications because of its potential to combine high endurance, non-volatility, and exceptional operating speed.
- ReRAM: Expands across artificial intelligence accelerators, neuromorphic computing, and embedded processing systems by offering promising scalability, lower operating power, and high-speed memory performance.
- PMC: Supports specialized industrial, aerospace, and defense applications requiring persistent storage reliability, environmental durability, and consistent operation under demanding mission-critical conditions.
Wafer Size
The Wafer Size segment of the Non-volatile Memory Market is anticipated to expand at a CAGR of 9.4–10.0% during 2026–2034. Larger wafer production enhances manufacturing efficiency, improves chip yield, lowers unit production costs, and enables higher-volume fabrication for advanced semiconductor memory products. Continued investments in fabrication facilities and process optimization are expected to strengthen production capacity throughout the forecast period.
- 200 mm: Continues supporting mature semiconductor manufacturing processes, specialty memory products, automotive electronics, industrial components, and embedded applications where production stability and established fabrication infrastructure remain strategically important.
- 300 mm: Represents the preferred manufacturing platform for advanced memory technologies because it enables greater production efficiency, higher throughput, improved economies of scale, and competitive cost optimization for high-volume semiconductor manufacturing.
End-user
The End-user segment is forecast to register a CAGR of 9.9–10.5% during 2026–2034. Expanding digitalization, connected infrastructure, intelligent mobility, and cloud computing continue to increase deployment across multiple industries. Higher storage performance, energy efficiency, and reliability remain essential purchasing criteria as organizations modernize digital infrastructure and adopt data-intensive computing environments.
- Consumer Electronics: Accounts for the largest deployment base, supported by smartphones, tablets, laptops, gaming consoles, wearable devices, and smart home products requiring high-density, energy-efficient persistent storage.
- Enterprise Storage: Benefits from expanding cloud computing, hyperscale data centers, virtualization, artificial intelligence workloads, and high-performance computing applications demanding reliable, scalable, and high-speed storage solutions.
- Healthcare: Increasingly adopts advanced memory technologies across diagnostic imaging equipment, portable medical devices, electronic health record systems, and connected healthcare infrastructure requiring dependable long-term data retention.
- Automotive: Demonstrates the fastest adoption across advanced driver assistance systems, infotainment, autonomous driving platforms, electric vehicles, and connected mobility solutions requiring durable, high-performance memory under demanding operating conditions.
Opportunity Snapshot
| End-user | Revenue Contribution | Trend Tag | Adoption Stage |
| Consumer Electronics | High | Edge AI | Mature |
| Enterprise Storage | High | Hyperscale SSD | Scaling |
| Healthcare | Medium | Digital Health | Scaling |
| Automotive | High | Software-Defined Vehicle | Emerging |
Non-Volatile Memory Market Growth Drivers and Impact Analysis
Expansion of Artificial Intelligence and High-Performance Computing Infrastructure
There is a notable surge in the need for storage solutions that provide high capacity and low latency due to the growing number of use cases of artificial intelligence, machine learning, and HPC systems. Tasks such as training big language models, analytics in real-time, and advanced simulations involve processing huge amounts of data that must be stored persistently in order to provide fast access to it, along with better durability. Data center capacity keeps growing in the case of hyperscale cloud providers, whereas enterprises strive to implement digital transformation projects. Semiconductor companies start developing new memory designs, enhancing controllers, and increasing efficiency in production processes. This makes the ecosystem facilitate cooperation between semiconductor manufacturers, cloud companies, hardware producers, and software developers in order to increase storage performance while minimizing power and cost usage.
Growing Automotive Electrification and Intelligent Mobility Systems
The move to electric vehicles, connected vehicles, and assisted driverless technologies has created consistent demand for quality memory that can perform in tough environmental settings. Modern cars come packed with a lot of electronics such as control units, infotainment technology, autonomous driving systems, battery management systems, as well as over-the-air software updates that call for security, performance and high-endurance persistent memory. More semiconductor content in cars further drives demand for years to come in both passenger and commercial vehicles. There continues to be more collaboration between automotive companies and semiconductor providers aimed at ensuring functional safety, cybersecurity and quality product in line with strict industry standards.
Government Support for Semiconductor Manufacturing and Supply Chain Resilience
National semiconductor strategies across North America, Europe, and the Asia Pacific are encouraging substantial investments in fabrication facilities, advanced packaging technologies, and semiconductor research capabilities. Governments are introducing financial incentives, research grants, and manufacturing support programs to strengthen domestic chip production and reduce dependence on geographically concentrated supply chains. These initiatives are encouraging capacity expansion, technology transfer, and workforce development while accelerating the commercialization of advanced memory products. Increased collaboration among semiconductor manufacturers, equipment suppliers, research organizations, and academic institutions is also fostering innovation across emerging memory architectures. Strengthened manufacturing resilience improves long-term supply stability, enhances competitiveness, and creates favorable conditions for sustained growth across consumer electronics, enterprise storage, automotive, healthcare, and industrial applications.
Non-Volatile Memory Market Future Trends
Transition Toward Higher-Layer 3D Memory Architectures
The industry is steadily moving toward higher-layer three-dimensional memory architectures to achieve greater storage density, improved energy efficiency, and lower cost per bit. This non-volatile memory market trends transition is enabling manufacturers to address the rapidly growing storage requirements of artificial intelligence platforms, hyperscale data centers, enterprise storage systems, and next-generation consumer electronics. Continuous advances in wafer processing, controller integration, and packaging technologies are improving device performance while extending product lifespan. As fabrication processes mature, higher-layer memory solutions are expected to become commercially viable across a broader range of applications, supporting increased production volumes and strengthening long-term competitiveness throughout the semiconductor ecosystem.
Increasing Integration of Emerging Persistent Memory Technologies
Emerging technologies including magnetoresistive RAM, resistive RAM, ferroelectric RAM, and other advanced persistent memory solutions are expected to gain wider commercial adoption over the coming years. Their ability to deliver faster write speeds, lower energy consumption, enhanced endurance, and improved reliability makes them attractive for edge computing, industrial automation, automotive electronics, healthcare equipment, and artificial intelligence hardware. Continued investments in research, pilot production, and ecosystem partnerships are expected to accelerate commercialization while reducing manufacturing costs. As application-specific requirements evolve, these technologies are likely to complement conventional flash memory rather than replace it, creating a more diversified and resilient memory landscape for future semiconductor innovation.
Non-Volatile Memory Market Opportunities
Expanding Semiconductor Manufacturing Investments Across Emerging Economies
Rising public and private investment in semiconductor fabrication presents a significant long-term opportunity for memory manufacturers, equipment suppliers, and technology partners. According to current non-volatile memory market forecasts, countries including India, Vietnam, Malaysia, and selected Middle Eastern economies are strengthening domestic semiconductor ecosystems through financial incentives, infrastructure development, and research collaborations. These initiatives encourage localization of production, improve supply chain resilience, and diversify manufacturing capacity beyond traditional hubs. Companies establishing strategic partnerships, regional fabrication capabilities, and technology transfer programs are expected to benefit from expanding demand across consumer electronics, automotive systems, industrial automation, healthcare devices, and cloud infrastructure while improving operational flexibility and reducing geopolitical supply risks.
Growing Demand for Edge Computing and Intelligent Connected Devices
The rapid expansion of edge computing environments creates new opportunities for advanced persistent memory technologies that deliver low latency, high endurance, and reduced energy consumption. Increasing deployment of industrial Internet of Things platforms, autonomous machines, smart factories, connected healthcare equipment, telecommunications infrastructure, and intelligent transportation systems requires dependable storage capable of processing data closer to the source. Manufacturers investing in application-specific memory solutions, secure embedded storage, and next-generation controller technologies will be well-positioned to address evolving customer requirements. Strategic collaboration with cloud providers, automotive manufacturers, industrial equipment producers, and telecommunications companies is expected to accelerate commercialization while supporting sustainable revenue growth across multiple high-value industry verticals.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for