
Light Emitting Diode (LED) Market Growth, Share & Trends by 2034
Coverage: by Technology (Surface-Mount Device, Chip-on-Board, Chip Scale Package, Others), Product Type (LED Lamps, LED Luminaires, LED Modules, Bare LED Components), Application and Installation Type (General Lighting, Automotive Lighting, Backlighting, UV/IR, New Installation, Retrofit/Replacement), and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPTE100000106
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : October 26, 2026


2025 Market Size
US$ 109.04 Bn
Base year value
2034 Forecast
US$ 208.53 Bn
Projected by 2034
CAGR 2026-2034
7.47 %
Growth rate
Addressable Market
US$ 1,431.37 Bn
(2026-2034)
The Light Emitting Diode Market size reached US$ 109.04 Billion in 2025 and is projected to reach US$ 208.53 Billion by 2034, expanding at a CAGR of 7.47% during 2026–2034. The market encompasses semiconductor light sources used across general illumination, displays, automotive systems, backlighting, signaling, and specialized applications. Continued improvements in efficacy, packaging, thermal management, controllability, and reliability are broadening LED deployment across residential, commercial, industrial, transportation, and consumer electronics environments.
North America remains a technology-intensive regional market, supported by commercial retrofit programs, energy-efficiency requirements, smart-building adoption, and automotive electronics. The region is estimated to expand at a CAGR of 7.0–7.8% during 2026–2034. Replacement of legacy lighting, connected controls, and demand for higher-performance components are strengthening the LED ecosystem, while advanced manufacturing and design capabilities support premium applications and the regional LED technology base.
Light Emitting Diode (LED) Market Assessment and Insights
- North America: The region accounted for 26–30% Light Emitting Diode Market share in 2025 and is expected to grow at a CAGR of 7.0–7.8% during 2026–2034, supported by commercial modernization, energy-efficiency policies, and connected lighting adoption.
- US: The US represented 74–78% share of North America in 2025 and is projected to expand at a CAGR of 7.1–7.9%, led by retrofit activity, automotive electronics, and smart-building projects.
- Europe: Europe held 22–26% share in 2025 and is projected to grow at a CAGR of 7.2–8.0%, with Germany, the UK, France, Italy, and Spain supporting efficient lighting replacement and connected infrastructure.
- Asia Pacific: Asia Pacific represented 34–38% share in 2025 and is forecast to expand at a CAGR of 8.0–8.8%, led by China, Japan, South Korea, and India through electronics manufacturing, urbanization, and industrial investment.
- Largest Segment: Surface-Mount Device technology held 46–52% market share in 2025 and is estimated to expand at a CAGR of 7.6–8.3%, supported by scalable packaging and broad luminaire adoption.
- High Growth Segment: UV/IR applications represented 6–10% share in 2025 and are projected to grow at a CAGR of 9.5–10.8%, supported by sensing, sterilization, inspection, and specialized industrial systems.
- Key companies analyzed in detail: Cree LED; Epistar Corp.; Nichia Corporation; ams-OSRAM AG; Siemens AG; Koninklijke Philips N.V.; Lumileds Lighting; General Electric; Samsung Electronics Co., Ltd.; Bridgelux, Inc.; SemiLEDS Corporation; Seoul Semiconductor Co., Ltd.; Toyoda Gosei Co., Ltd.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
Technology evolution has seen LEDs evolve from simple solid-state light emitters to more advanced application-oriented technologies that are efficacious, high-quality in color, thermally robust, miniaturized, and integrable. Technological advancements in packaging including surface-mounting, chip-scale packaging, and chip-on-board technologies have seen better optical density and design flexibility. Meanwhile, there is an expectation of tighter tolerances and higher reliability among automotive, display, and specialty lighting applications. Adoption of LEDs is highlighted by the IEA as one of the significant lighting-efficiency transitions, with policies and standards driving replacement cycles.
In the future, there will be increased investment in intelligent emitters, highly dense packages, microLED technologies, UV-C technologies, and optical component technologies customized to certain applications. Moreover, emerging economies are seeing an increase in the penetration of LEDs through urban infrastructure and industrial transformation. The importance of energy efficiency and minimization of hazardous materials will drive the replacement demand, while the emergence of electric vehicles and digitally controlled lighting creates further opportunities for semiconductor integration.
Light Emitting Diode (LED) Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 109.04 Billion |
| Market Size by 2034 | US$ 208.53 Billion |
| Global CAGR (2026 - 2034) | 7.47% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Light Emitting Diode (LED) Market Analysis
Light Emitting Diode Market development is driven by substitution of incandescent, halogen, and fluorescent lighting, increased need for efficient lighting solutions, and growing electronic content in vehicles and display applications. The value chain covers semiconductors, epitaxy wafers, LED chips, packaging services, phosphors, LED drivers, modules, luminaires, and systems integration. Supply dynamics are defined by chip production capacities, availability of substrates, yield of packaging, and manufacturing location concentration. The competitive edge of product offerings in the Light Emitting Diode Market becomes more focused on optical characteristics, thermal management, color stability, and application-oriented reliability.
Light Emitting Diode Market demand is developing beyond traditional lighting applications. LEDs are used in automotive signaling and headlights, LCD backlights, displays, sensors, ultraviolet disinfection, machine vision, horticulture, and communications. Thus, manufacturers have to differentiate their products on the level of components specifications and system applications. Resilience of the supply chain is becoming strategically significant as companies expand manufacturing locations and qualify new sources for their components. Energy efficiency policies of the governments, building regulations, and minimal performance standards also affect selection and time of replacement decisions.
Positioning is increasingly determined by the capacity to integrate semiconductor technology with packaging, optics, thermal engineering, and application development. In the Light Emitting Diode Market report, Nichia Corporation and Lumileds Lighting highlight their performance-based emitters whereas ams-OSRAM AG highlights their substantial exposure to the automotive and specialty optical segments. Samsung Electronics Co., Ltd., Seoul Semiconductor Co., Ltd., and Bridgelux, Inc. focus on package differentiation and application-based technology.
The Light Emitting Diode Market trends are changing towards microLED, high density emitters, UV-C, intelligent automotive lighting, and connected lighting. Koninklijke Philips N.V. is involved through its lighting systems and connected products, and Siemens AG is involved through its ecosystems for buildings and industry. Epistar Corp., SemiLEDS Corporation, Toyoda Gosei Co., Ltd., and Cree LED have established positions in semiconductor and components. The competitive advantage is becoming dependent on qualification cycles, intellectual property, manufacturing yield, co-development with customers, and global supply capabilities.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
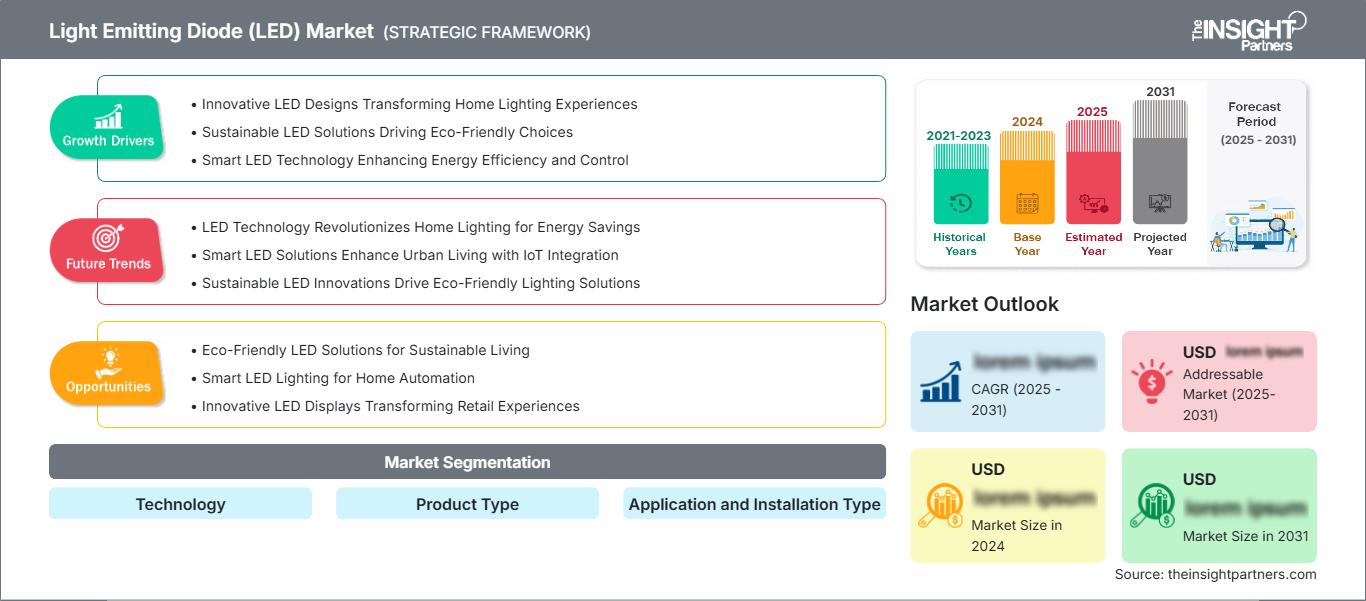
Light Emitting Diode (LED) Market: Strategic Insights
Regional Insights
North America Light Emitting Diode Market
North America accounted for 26–30% Light Emitting Diode Market share in 2025 and is projected to grow at a CAGR of 7.0–7.8% through 2034. USA is the main regional market while Canada fuels the demand via modernization and efficiency in building and infrastructures. The retrofitting process is vital since LED lighting can be implemented to existing luminaries and minimize the installation process. Smart lighting control systems and occupancy sensors and digital lighting control devices have been integrated in many commercial projects.
Another avenue of growth for LED lighting is the use of automotive electronics as cars will start incorporating adaptive lighting, displays, and electronic lighting control systems. Industrial buildings are now switching from high bay lights and other task lighting sources to networked LED lighting systems. North American companies have well-developed engineering expertise, sales channels and customers.
U.S. Light Emitting Diode Market
The US represented 74–78% of North America's 2025 Light Emitting Diode Market and is expected to expand at a CAGR of 7.1–7.9% through 2034. Retrofitting applications, industrial installations, automotive applications, and intelligent buildings continue to be significant application areas.
Replacement of old luminaires along with increasing use of controls are driving US demand. Cree LED Lighting and General Electric have already created brand recognition, whereas international companies cater to the needs of automotive, electronics, commercial, and architectural segments. Trends in terms of applications are shifting toward tunable white lighting, occupancy sensing controls, addressable technology, and high-intensity luminaires. Modernization of buildings will lead to creation of opportunities where LEDs are incorporated into energy management systems, thus making lighting a component of facility automation.
Europe Light Emitting Diode Market
Europe held 22–26% share in 2025 and is projected to grow at a CAGR of 7.2–8.0%. The United Kingdom is still an important market for retrofits and smart-lighting solutions, with commercial applications, infrastructural needs, and residential building upgrades driving the demand. The market leader is Germany, driven by automation in industry, automotive manufacturing, and investments in efficiency. Other countries that make their contributions include France, Italy, and Spain, which drive demand with urban modernization projects, hotel lighting systems, transportations, and architecture lighting initiatives. Increasingly, European demand places more value on efficient, smart, and durable products.
European regulations provide an enabling environment for replacing old and inefficient technologies with more effective and sustainable solutions. Automotive lighting is particularly important in Germany, while infrastructural modernizations play a part in driving demand in Western and Southern Europe. Two major companies that have high regional importance include Koninklijke Philips N.V. and ams-OSRAM AG, along with specialists in semiconductors.
APAC Light Emitting Diode Market
APAC held 34–38% share in 2025 and is forecast to grow at a CAGR of 8.0–8.8%. The dominance of China is sustained by the strong manufacturing abilities, construction activities, and LED production capabilities within the country. Japan and South Korea possess advanced semiconductor and display technologies while India and Australia provide demand due to urbanization and commercial activities.
The region has a highly developed network for the electronics supply chain and increasing capabilities. China handles mass component production, Japan concentrates on quality and specialization, and South Korea remains important in displays and semiconductors. India has increased the usage of LEDs for construction purposes while Australia aids in providing commercial and outdoor lighting systems.
Middle East & Africa Light Emitting Diode Market
Middle East & Africa is projected to expand at a CAGR of 9.0–10.0%, supported by urban infrastructure, energy-efficient buildings, tourism projects, and industrial development. Saudi Arabia leads the market, followed by the UAE and South Africa that contribute to key demand generators in commercial, infrastructural, and industrial applications.
Urbanization in Saudi Arabia and the UAE gives rise to need for architectural, outdoor, roadway, hospitality, and intelligent building lights. South Africa generates demand via commercial renovations, industrial plants, and infrastructure development. Replacement of old-fashioned lighting continues to be a key avenue of adoption in the RoMEA region. High ambient temperature further adds significance to proper thermal management, robustness of product design, and efficient driver operation.
Segmentation Analysis
Technology
The Technology segment encompasses packaging and semiconductor architectures that determine optical performance, thermal behavior, reliability, and integration flexibility. Surface-mounted designs remain broadly adopted because they support automated manufacturing and compact luminaires, while COB and CSP architectures serve applications requiring higher density or miniaturization. The segment is projected to grow at a CAGR of 7.5–8.2%. The Light Emitting Diode Market scope increasingly includes specialized packages optimized for automotive, display, UV, and sensing applications.
- Surface-Mount Device (SMD): SMD LEDs provide scalable assembly, compact footprints, and broad compatibility with automated production, making them central to general lighting, displays, signage, and automotive electronics.
- Chip-on-Board (COB): COB integrates multiple LED chips on a common substrate, supporting high luminous density, uniform illumination, and compact optical designs for professional lighting.
- Chip Scale Package (CSP): CSP technologies reduce package dimensions and improve optical integration, supporting miniaturized automotive, display, mobile, and high-density lighting applications.
- Others: Other architectures address specialized requirements involving thermal performance, optical configuration, high-power operation, or application-specific mechanical constraints.
Product Type
Product Type determines how LED semiconductor technology reaches equipment manufacturers, lighting producers, and end users. Lamps and luminaires represent mature commercial formats, while modules and component-level products provide greater design flexibility for OEMs. The segment is projected to grow at a CAGR of 7.1–7.8%. Increasing integration of drivers, optics, sensors, and controls is encouraging manufacturers to move toward application-ready products.
- LED Lamps: LED lamps are widely used for direct replacement applications, providing standardized form factors for residential, commercial, hospitality, and institutional lighting upgrades.
- LED Luminaires: Luminaires integrate LEDs with optics, thermal structures, drivers, and housings, enabling application-specific performance for offices, roads, factories, retail spaces, and public infrastructure.
- LED Modules: Modules provide configurable light engines for luminaire manufacturers and system integrators, supporting customized form factors, color characteristics, and optical performance.
- Bare LED Components: Component-level emitters serve OEM and specialist applications where customers require control over optical, electrical, thermal, and mechanical system design.
Application and Installation Type
Application and Installation Type captures both the downstream use of LEDs and the project pathway through which products are deployed. General lighting remains broad, while automotive, displays, backlighting, and UV/IR applications provide specialized demand. New installations increasingly incorporate smart controls from inception, whereas retrofit projects prioritize compatibility. The segment is projected to grow at a CAGR of 7.8–8.6%.
- General Lighting: Residential, commercial, industrial, roadway, and architectural lighting form the largest application base, with demand shaped by efficiency, maintenance, controllability, and fixture compatibility.
- Automotive Lighting: LEDs support headlamps, rear lamps, signaling, interior illumination, and adaptive systems, with electrification increasing demand for electronically controlled and design-flexible lighting.
- Backlighting: LEDs remain important for displays and electronic equipment, where compactness, brightness, color quality, and power efficiency influence component selection.
- Display & Signage: High-brightness and fine-pitch LED technologies support direct-view displays, digital signage, advertising, stadiums, transportation information systems, and immersive visual environments.
- UV/IR: Ultraviolet and infrared LEDs serve sterilization, sensing, inspection, communications, medical, industrial, and security applications requiring wavelength-specific optical output.
- New Installation: New projects allow LEDs, controls, sensors, and power-management systems to be designed as integrated solutions, supporting higher functionality and optimized lifecycle performance.
- Retrofit/Replacement: Retrofit projects focus on replacing inefficient legacy sources while preserving existing infrastructure, making compatibility, installation time, maintenance savings, and regulatory compliance important purchasing criteria.
Opportunity Snapshot
| Application and Installation Type | Revenue Contribution (High/Medium/Low) | Trend Tag | Adoption Stage |
| General Lighting | High | Smart Retrofit | Mature |
| Automotive Lighting | High | Adaptive Beam | Scaling |
| Backlighting | Medium | Display Efficiency | Mature |
| Display & Signage | Medium | Fine Pitch | Scaling |
| UV/IR | Low | UV-C Systems | Emerging |
| New Installation | High | Integrated Controls | Scaling |
| Retrofit/Replacement | High | Legacy Conversion | Mature |
Light Emitting Diode (LED) Market Growth Drivers and Impact Analysis
Global Replacement of Inefficient Lighting Technologies
The replacement of older lighting solutions such as incandescent, halogen, fluorescent and others is also a critical requirement driver, since LEDs provide a combination of efficiency, longevity, controllability and ever more favorable cost-benefit equation. Energy efficiency measures, minimum requirements and public procurements further support replacement waves in buildings and outdoor applications. For the International Energy Agency, the adoption of LED technology is still an important factor in the development of lighting efficiency, but its analysis focuses on the next step in the adoption process, that is, more advanced and efficient solutions. This makes the demand for lamps, luminaires, modules, drivers and controllers permanent, especially when the energy savings can be made to justify the upgrade.
Expansion of Automotive and Electronic Lighting Content
In the auto industry, more and more manufacturers incorporate LED lights into their headlamps, adaptive headlights, tail lights, signaling devices, interior, and interactive features of the car. This tendency is reinforced by electric cars since modern cars integrate lighting with the electronic architecture, car displays, sensors, and software-controlled mechanisms. Thanks to LEDs, manufacturers can create smaller optical designs, adjust light beams dynamically, style lights, and provide better illumination of roads. At the same time, LEDs are still used in consumer electronics to backlight screens and even provide direct-view designs.
Growth of Connected and Intelligent Lighting Infrastructure
Connected lighting technologies convert LEDs from simple light fixtures to infrastructure that is controllable through digital means. With sensors, wireless technology, occupancy sensing, daylight harvesting, dimming, and remote management features, lighting can be optimized in relation to the occupancy and operational state. Such evolution brings about a growing need for devices capable of functioning with such smart lighting systems. Commercial and industrial buildings, warehouses, campuses, and highway systems are especially appropriate for connected lighting systems because of the vast coverage area and operation hours. With the integration of lighting with building management systems and energy management systems, differentiation is no longer based on emitter performance only.
Light Emitting Diode (LED) Market Future Trends
MicroLED and High-Density Semiconductor Integration
LED Market Trends are shifting towards small form factors, high pixel density, and integration of optics systems. MicroLED technology is advancing from the research phase to application-specific areas where brightness, contrast, speed, reliability, and size offer benefits. In addition, semiconductor manufacturers have advanced in terms of chip level packaging and optics coupling to minimize the size of the system. Markets that will be significant early adopters include automotive displays, augmented reality systems, high-end TVs, signs, and visualizers. Success will depend on yield, mass transfer economics, defect handling, and repair ability, therefore making production engineering as crucial as LED performance.
Intelligent, Human-Centric, and Spectrally Tunable Lighting
Today, lighting solutions are increasingly being developed considering controlled spectra, color temperatures, occupancy trends, and needs of people. Human-centric technologies allow the characteristics of light to be adjusted based on time, location, or activities, whereas intelligent control makes it possible to link the luminaire with the sensor as well as building platforms. With technological advancements in semiconductors, more precise control of the spectra and lower energy consumption is achieved. For instance, Seoul Semiconductor Co., Ltd. keeps promoting the SunLike technology that works with a spectrum like natural sunlight.
Light Emitting Diode (LED) Market Opportunities
Expansion of UV-C and Specialized Wavelength Applications
UV-C LEDs provide an opportunity to extend semiconductor lighting into water treatment, air treatment, surface disinfection, industrial inspection, and other wavelength-specific applications. Nichia Corporation has continued advancing UV-C technology, including a 280 nm product that entered mass production after demonstrating higher wall-plug efficiency than its earlier generations. The commercial opportunity extends beyond conventional lighting because customers increasingly seek mercury-free alternatives with compact form factors and controllable operation. Suppliers able to improve optical output, thermal management, lifetime, and cost can target specialized applications where performance requirements create higher barriers to entry and reduce direct price competition.
Localized Manufacturing and Application-Specific LED Solutions
The Light Emitting Diode Market Forecasts point toward opportunities for manufacturers that combine regional production with application-specific engineering. Localized supply can reduce logistics exposure and improve responsiveness for automotive, industrial, infrastructure, and commercial customers. At the same time, specialized emitters designed for thermal constraints, color requirements, optical geometry, or regulatory specifications can command stronger customer relationships than standardized components. Investments in packaging automation, testing, qualification, and design support can therefore strengthen competitive positioning. Partnerships with luminaire manufacturers, automotive Tier suppliers, display companies, and system integrators can accelerate qualification and create recurring demand for differentiated component platforms.
Recent Developments
- August 2026: ColorJet Group is set to unveil its latest innovation, the Verve LED Z20, at Media Expo Delhi 2026, scheduled from 17-19 September 2026 at Bharat Mandapam, New Delhi. The new flatbed UV printer is engineered to expand the possibilities of UV printing beyond conventional flat substrates, enabling high-quality printing on curved, contoured and uneven surfaces. With a print area of 2500 × 1300 mm, the Verve LED Z20 is designed for specialty and industrial applications where conventional flatbed UV printers may face functional limitations.
- April 2026: Nuvoton Technology announced today the start of mass production of a "high-power violet laser diode (402 nm, 4.5 W) [1]" that achieves industry-leading class optical output in a 9.0 mm diameter CAN package (TO-9) [2]. This product achieves 1.5 times the optical output compared to our conventional product through our proprietary device structure and heat dissipation design technology and contributes to improving production throughput in optical equipment such as maskless lithography systems. Furthermore, adding this product to our lineup enables our product portfolio to support major photosensitive materials used in advanced semiconductor packaging.
- January 2026: Nichia, the world's largest LED/Laser Diode manufacturer and inventor of the high-brightness blue and white LEDs, is pleased to announce the full-scale launch of its “Mercury-Free Project,” an initiative to replace mercury lamps used within Nichia with LED technology. This project is based on the concept of “sustainable manufacturing” and aims to replace all mercury lamps used on Nichia's production lines with LEDs by 2030. To achieve this goal, Nichia will install devices using LEDs and accelerate the development of technologies necessary to achieve this goal.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for