
Wireless Infrastructure Market Size, Share & Forecast by 2034
Coverage: by Network (2G/3G, 4G, 5G); Component (Macrocell Radio Access Networks (RAN), Small Cells, Remote Radio Heads (RRH), Distributed Antenna Systems (DAS), Cloud RAN, Carrier Wi-Fi, Mobile Core, Backhaul) , and Geography (North America, Europe, Asia Pacific, and South and Central America)
- Status : Data Released
- Report Code : TIPRE00007635
- Category : Electronics and Semiconductor
- No. of Pages : 150
- Available Report Formats :


- Last update date : September 28, 2026


2025 Market Size
US$ 276.18 Bn
Base year value
2034 Forecast
US$ 640.97 Bn
Projected by 2034
CAGR 2026-2034
9.81 %
Growth rate
Addressable Market
US$ 4,085.52 Bn
(2026-2034)
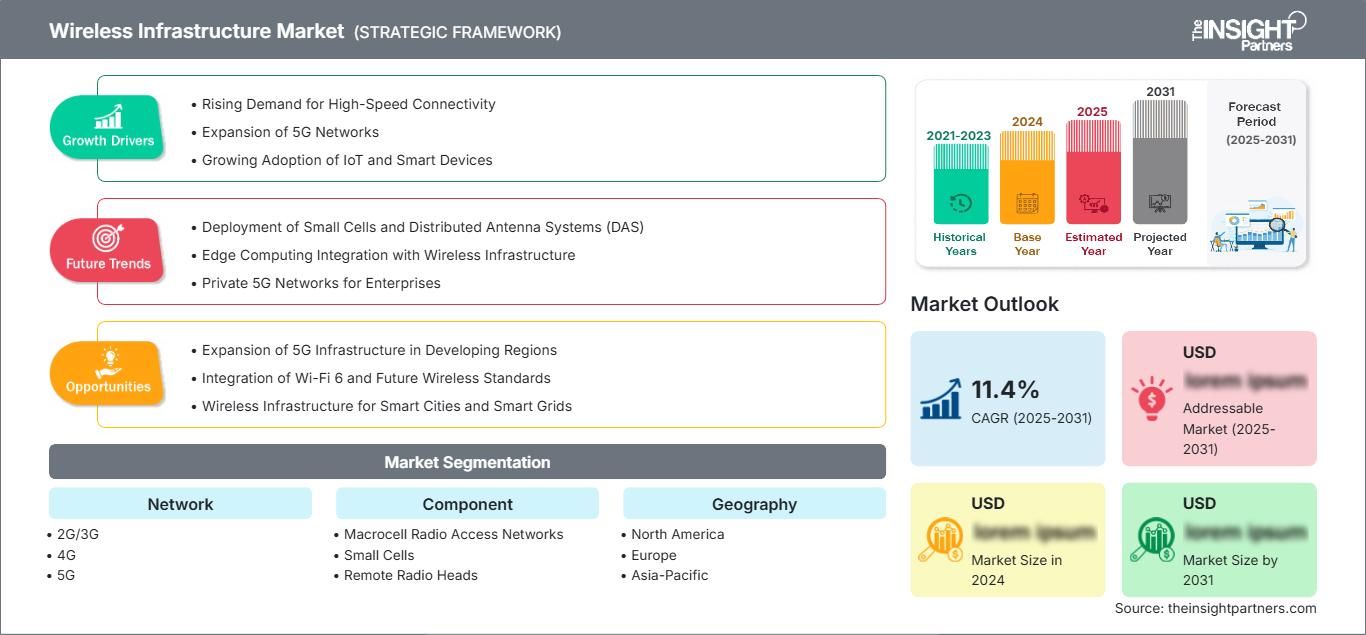
The wireless infrastructure market is valued at US$ 276.18 Billion in 2025 and is projected to reach US$ 640.97 Billion by 2034, expanding at a CAGR of 9.81% during 2026–2034. The market encompasses radio access, core, transport, and wireless access technologies supporting mobile connectivity across consumer, enterprise, industrial, and public-sector environments. Investment is increasingly shifting toward 5G capacity, network modernization, cloud-native architectures, and intelligent automation as operators prepare for sustained data growth.
North America is positioned for steady expansion, supported by 5G-Advanced deployment, enterprise connectivity, spectrum utilization, and network modernization. The wireless infrastructure market size in the region is expected to advance at an estimated 8.5–10.0% CAGR through 2034. Operator investments in AI-enabled network management, private wireless, edge computing, and higher-capacity radio systems are strengthening the infrastructure replacement cycle across the US and Canada.
Wireless Infrastructure Market Assessment and Insights
- North America: North America is expected to account for approximately 27–31% of global market value in 2025 and expand at a CAGR of 8.5–10.0% between 2026–2034, supported by 5G-Advanced, enterprise wireless, and spectrum modernization.
- US: The US represents approximately 23–27% of global value in 2025 and is expected to grow at 8.4–9.8% CAGR through 2034, driven by nationwide 5G capacity expansion and private wireless adoption.
- Europe: Europe is estimated to hold 20–24% share in 2025 and grow at 7.8–9.2% CAGR during 2026–2034. Germany, the UK, France, Italy, and Spain remain important deployment markets, with modernization increasingly emphasizing energy efficiency and cloud-native RAN.
- Asia Pacific: Asia Pacific is estimated to represent 34–39% share in 2025 and grow at 10.5–12.5% CAGR through 2034. China, Japan, South Korea, and India lead regional deployment momentum through dense 5G rollouts, industrial digitization, and supportive connectivity policies.
- Largest Segment: The 5G network segment is estimated to represent 52–57% share in 2025, expanding at 11.0–13.0% CAGR through 2034 as operators prioritize capacity, coverage, and advanced enterprise services.
- High Growth Segment: Cloud RAN is estimated to hold 7–11% share in 2025 and expand at 15.0–18.0% CAGR as virtualization, automation, and flexible infrastructure become more important.
- Key companies analyzed in detail: ADTRAN, Inc.; Cisco Systems, Inc.; Telefonaktiebolaget LM Ericsson; Huawei Technologies Co., Ltd.; Motorola Solutions, Inc.; NEC Corporation; Nokia Corporation; Qualcomm Technologies, Inc.; Samsung Electronics Co., Ltd.; ZTE Corporation.
Source: The Insight Partners' analysis based on proprietary research, government publications, company annual reports, investor presentations, industry databases, and expert interviews.
The wireless infrastructure market has evolved from hardware-centric cellular deployment toward software-defined, multi-layer network environments. 4G remains important for coverage and legacy services, while 5G introduces massive MIMO, virtualization, network slicing, edge integration, and higher spectrum efficiency. Production dynamics increasingly favor modular radios, software-upgradable platforms, energy-efficient semiconductors, and cloud-native network functions. ITU data indicates that 55.1% of the world's population was covered by at least 5G in 2025, while 96.3% had at least 3G coverage, illustrating the simultaneous operation of mature and emerging network generations.
Looking forward, the market will increasingly be shaped by investment in AI-native RAN, Open RAN interoperability, private networks, and 5G-Advanced capabilities. The Wireless Infrastructure Market report highlights that regulatory efforts around spectrum availability, infrastructure sharing, energy consumption, and national digitalization will influence deployment economics. Emerging economies are expected to combine broad 4G coverage with targeted 5G investments, while mature markets increasingly concentrate spending on capacity upgrades, automation, indoor coverage, and enterprise-grade services rather than uniform nationwide expansion.
Wireless Infrastructure Market Report Scope
| Report Attribute | Details |
|---|---|
| Market size in 2025 | US$ 276.18 Billion |
| Market Size by 2034 | US$ 640.97 Billion |
| Global CAGR (2026 - 2034) | 9.81% |
| Historical Data | 2021-2024 |
| Forecast period | 2026-2034 |
Wireless Infrastructure Market Analysis
Demand is being reinforced by rising mobile data consumption, enterprise digitization, connected devices, and the migration of industrial processes toward wireless connectivity. The wireless infrastructure market growth is particularly linked to the need for higher throughput and lower latency in factories, logistics facilities, utilities, healthcare campuses, and transportation systems. ITU estimates show 99 active mobile-broadband subscriptions per 100 inhabitants globally in 2025, demonstrating the mature installed base that operators must continuously upgrade.
The ecosystem includes spectrum holders, mobile network operators, infrastructure vendors, semiconductor suppliers, software providers, tower companies, system integrators, and enterprise customers. Supply dynamics are therefore influenced by radio component availability, semiconductor efficiency, fiber backhaul, cloud computing capacity, and installation economics. Operators increasingly evaluate total cost of ownership rather than equipment price alone, placing greater emphasis on power consumption, automation, lifecycle support, software compatibility, and upgradeability.
The wireless infrastructure market analysis indicates a competitive environment in which scale, radio performance, software capability, intellectual property, and long-term operator relationships determine positioning. Ericsson, Nokia, Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd., and ZTE Corporation compete strongly across RAN and network modernization, while Cisco Systems, Inc., NEC Corporation, Qualcomm Technologies, Inc., and ADTRAN, Inc. participate across complementary networking, enterprise, access, and Open RAN ecosystems.
Investment priorities are shifting toward software-defined RAN, Cloud RAN, AI-assisted optimization, and energy-efficient radio equipment. Nokia's 2026 UK agreement with Virgin Media O2 demonstrates continued spending on Massive MIMO, baseband modernization, automation, and 5G-Advanced readiness. Qualcomm Technologies, Inc. also highlighted commercial momentum for Open RAN in 2025 through deployments involving Viettel and NTT DOCOMO. According to the Wireless Infrastructure Market forecast, these developments illustrate increasing diversification of infrastructure architectures alongside continued demand for established RAN platforms.
● REPORT CUSTOMIZATION
Tailor This Report To Align With Your Specific Business Requirements
This report can be customized to align precisely with your business objectives, scope, and target markets. Customization options include tailored segmentation, geography, competitive analysis, and strategic insights to support informed decision-making.
Customize This Report →WHAT YOU CAN ADJUST
- ● Segmentations
- ● Geography
- ● Competitive Analysis
- ● Language Preferences
Wireless Infrastructure Market: Strategic Insights
Regional Insights
North America Wireless Infrastructure Market
North America is estimated to hold 27–31% of global Wireless Infrastructure Market value in 2025, with growth of 8.5–10.0% CAGR during 2026–2034. These include the region's advanced 5G coverage, adoption of enterprise technology, and further investment in spectrum efficiency. According to GSMA, in the 2025 regional assessment, the percentage of 5G connections was 60% in both the US and Canada, while carriers were working towards 5G-Advanced service delivery. These factors make recurring radio upgrades and capacity expansion possible.
The investments in this region are shifting to focus on dense urban capacity, private wireless, edge computing, and network automation. Cloud-native network infrastructure and AI-driven network operation have become more relevant as carriers look for cost savings. The mix of a well-established customer base and heavy data consumption makes it a replacement-based opportunity and not a first-time connectivity one. Canada makes contributions through a national 5G upgrade, while the US continues to be the leading investment hub in the region due to its size and advanced spectrum use.
U.S. Wireless Infrastructure Market
The US is estimated to represent 23–27% of global Wireless Infrastructure Market value in 2025 and approximately 78–87% of North American value, expanding at an 8.4–9.8% CAGR through 2034. This country has high levels of deployment of 5G alongside ongoing need for enhanced capacity, rural, enterprise, and private wireless solutions. The leading service providers are still upgrading their radio infrastructure while enhancing their spectrum management capabilities and site density.
Some of the vendors active in the market include Ericsson, Nokia Corporation, Samsung Electronics Co., Ltd., Cisco Systems, Inc., Qualcomm Technologies, Inc., among others. Application areas that have been trending lately include industrial automation, logistics, public safety, connected transport, and fixed wireless access. Private 5G solutions are also being tested by some enterprises for guaranteed performance and control. This means that there is now a need for infrastructure spending going beyond the consumer mobile services sector.
Europe Wireless Infrastructure Market
Europe is estimated to account for 20–24% of global Wireless Infrastructure Market value in 2025 and expand at 7.8–9.2% CAGR through 2034. A good pipeline of modernization projects is observed in the UK, where operators focus on spectrum efficiency, standalone 5G and extended geographic coverage. Germany is an important market for industrial connectivity, where the automotive sector, manufacturing, logistics and utility companies support private and public 5G rollouts. France is focused on enterprise connectivity and network modernization, whereas Italy and Spain are developing 5G coverage, fiber-connected transport networks and digital infrastructure. The German market is likely to stay ahead of other European markets due to its industry and enterprise demands.
Energy efficiency and network automation become more relevant purchasing criteria in Europe. Collaboration between Nokia and Telefónica Germany, as well as the agreement between Nokia and Telecom Italia, proves continued investments in AI-ready RAN, Massive MIMO, remote radio heads and sustainable network modernization. In addition, digital sovereignty, infrastructure sharing, spectrum and cybersecurity policies play their role in choosing suppliers, making such companies as Nokia more attractive.
APAC Wireless Infrastructure Market
APAC is estimated to represent 34–39% of the Wireless Infrastructure Market share in 2025 and grow at 10.5–12.5% CAGR through 2034, making it the leading regional growth engine. China, Japan, South Korea, India, and Australia are combining their significant investments in 5G with the digitization of industries. According to GSMA, 39 commercial 5G networks existed in nine countries within the region by June 2025, with 17 standalone networks.
While China continues to lead as the largest market within the region, India is a key expansion point. The ITU states that India achieved a coverage rate of 82.2% by at least 5G technology among its population in 2024. Programs for government digitalization, manufacturing investments, smart cities development, and enterprise connectivity will be responsible for maintaining infrastructure needs.
Middle East & Africa Wireless Infrastructure Market
The Middle East and Africa Wireless Infrastructure Market is expected to grow at 9.0–11.0% CAGR through 2034, with Saudi Arabia leading the regional opportunity. In the UAE, development in 5G-Advanced and enterprise connectivity continues to take place. In South Africa, the importance of infrastructure development persists. Infrastructure growth is made possible through smart city initiatives, cloud computing, digitalization, and national connectivity strategies.
There is a high correlation between energy infrastructure and telecommunication infrastructure development in the region. This is because there is a need for operators who have radios, enhanced backhaul capacity, and adequate coverage of dispersed geographical users. The Ericsson deal of 2025 with e& UAE involved the enhancement of 5G RAN as well as 5G-Advanced and RedCap capability, indicating a move towards advanced network architecture.
Segmentation Analysis
Network
The Network segment is expected to expand at 10.0–12.0% CAGR during 2026–2034. Demand is transitioning from legacy network maintenance toward 5G capacity, standalone architectures, and 5G-Advanced. Operators continue balancing broad 4G coverage with selective 5G densification, creating a multi-generation environment where modernization must preserve service continuity and maximize spectrum efficiency. Current Wireless Infrastructure Market trends indicate growing investment in network virtualization, Open RAN deployments, spectrum optimization, and AI-driven network management to improve capacity, efficiency, and service quality across evolving wireless ecosystems.
- 2G/3G: 2G/3G infrastructure remains strategically relevant for legacy voice, machine-to-machine connectivity, and coverage in selected markets. Its role is gradually narrowing as operators refarm spectrum toward more efficient technologies while maintaining essential services during transition periods.
- 4G: 4G remains an essential capacity and coverage layer across developing and mature markets. Demand is sustained by affordable smartphones, extensive geographic coverage, and applications where LTE performance remains sufficient for consumer and enterprise requirements.
- 5G: 5G commands increasing investment because of higher capacity, lower latency, massive device support, and enterprise use cases. Standalone deployment, 5G-Advanced, fixed wireless access, and industrial connectivity are expanding their strategic importance.
Component
The Component segment is projected to grow at 9.0–11.0% CAGR through 2034. Spending is moving toward an integrated, software-manageable infrastructure capable of supporting multiple radio generations and deployment environments. Operators increasingly assess components according to power efficiency, scalability, interoperability, automation capability, and lifecycle economics rather than standalone hardware performance.
- Macrocell Radio Access Networks: Macrocell Radio Access Networks remain central to wide-area coverage and capacity. Investment focuses on higher spectral efficiency, Massive MIMO, energy optimization, and software upgrades that extend equipment usefulness across successive network generations.
- Small Cells: Small Cells support capacity densification in urban, enterprise, transport, and indoor environments. Their strategic importance is rising where macro sites face coverage limitations, especially in high-traffic venues and buildings requiring localized connectivity.
- Remote Radio Heads: Remote Radio Heads enable flexible radio deployment and improved site architecture. Demand is linked to multi-band networks, distributed architectures, and modernization programs seeking greater coverage while managing installation complexity and energy consumption.
- Distributed Antenna Systems: Distributed Antenna Systems remain important for indoor and venue coverage. Airports, hospitals, campuses, stadiums, and commercial buildings use distributed architectures where uniform signal quality and multi-operator support are operational priorities.
- Cloud RAN: Cloud RAN is gaining strategic attention through virtualization, centralized processing, automation, and flexible resource allocation. Adoption is strongest among operators evaluating software-defined architectures and seeking greater operational agility across distributed network environments.
- Carrier Wi-Fi: Carrier Wi-Fi extends wireless capacity using managed Wi-Fi infrastructure integrated with operator services. It remains strategically useful for offloading traffic, indoor connectivity, enterprise services, and complementary access in high-density locations.
- Mobile Core: Mobile Core modernization supports network slicing, standalone 5G, automation, policy control, and cloud-native service delivery. Operators increasingly require flexible cores capable of supporting differentiated consumer, enterprise, and industrial services.
- Backhaul: Backhaul provides the transport foundation linking radio sites to core infrastructure. Fiber expansion, microwave modernization, synchronization, and higher-capacity transport remain important as 5G increases traffic volumes and performance requirements.
Opportunity Snapshot
| Network | Revenue Contribution | Trend Tag | Adoption Stage |
| 2G/3G | Low | Legacy Sunset | Mature |
| 4G | High | LTE Capacity | Mature |
| 5G | High | 5G Advanced | Scaling |
Wireless Infrastructure Market Growth Drivers and Impact Analysis
5G-Advanced Capacity Requirements Are Extending Infrastructure Investment
The rollout of enhanced 5G services is driving further infrastructural demands beyond the phase of network buildout. In the present scenario, operators have to invest in further capacities in terms of radios, efficiencies in spectrum usage, enhancements in baseband technology, and denser sites in order to cater to the increased amount of traffic and enterprise loads. It affects equipment vendors, tower operators, semiconductor manufacturers, and software providers of the network. Moreover, 5G-advanced drives incremental investments in technologies like RedCap, positioning, automation of the network, and enhancements in quality of service management. With the growth of 5G networks, operators can focus on adding further capacities in selected locations rather than undertaking nationwide construction phases. It results in a highly selective yet continuous CAPEX environment, where CAPEX is focused on areas that offer good operational performance from networks.
Enterprise Digitalization Is Expanding Wireless Infrastructure Beyond Consumer Mobility
Enterprises’ connectivity is creating a larger addressable market by bringing wireless networks into the factory, warehouse, port, mining site, utilities, hospital, and infrastructure settings. Private wireless networks enable the organization to leverage mobility, deterministic connectivity, device management, and security in relation to OT systems. The resultant demand is different from traditional consumer-oriented networks in that consumers judge based on reliability, flexibility, application capability, and life cycle capability. This scenario is driving infrastructure vendors to create modular platforms that incorporate radios, core capabilities, edge computing, orchestration, and security. The effect is notable especially in the industrial setting, where wired extension could be expensive or disruptive. In the digitization of industrial equipment and processes, wireless connectivity takes the form of an operational layer rather than an access layer.
Energy Efficiency and Automation Are Reshaping Network Procurement
Network power consumption is gradually emerging as an essential factor in operator operational costs. Higher volume of traffic and denser radio deployment will require increased power consumption unless there is greater efficiency in terms of equipment, software, and operations. Thus, vendors compete with each other in power savings features, energy-aware scheduling, efficient semiconductor technologies, and automated networks. Automation also decreases the number of people needed for optimization, fault management, configuration, and performance management of networks that become increasingly more complicated and use multiple vendor technologies. The commercial implications of the situation lie in changing purchase criteria towards full-cycle economics. Modernization becomes viable when new infrastructure both expands capacities and saves on power or maintenance expenses. Such a situation will favor vendors that can prove their efficiency gains while providing the same level of coverage and performance in mature markets.
Wireless Infrastructure Market Future Trends
AI-Native RAN Will Become a Core Network Architecture Priority
AI-native RAN is likely to move from experimental architecture toward broader commercial deployment as operators seek autonomous optimization and new revenue models. Artificial intelligence can analyze traffic conditions, spectrum utilization, energy consumption, faults, and application requirements in near real time. The wireless infrastructure market trends will increasingly reflect convergence between network computing and AI workloads, allowing infrastructure to support connectivity alongside distributed intelligence. Future architectures may dynamically allocate computing resources between radio processing and AI applications according to traffic and service priorities. This could improve utilization while enabling operators to offer enterprise AI services at network edges. Vendors with strong orchestration, accelerator, and software capabilities are positioned to benefit as network intelligence becomes embedded across RAN, core, transport, and operational systems rather than deployed as an isolated management layer.
Open and Cloud-Native Architectures Will Increase Infrastructure Interoperability
Open interfaces and cloud-native solutions are forecast to become increasingly significant as operators look to increase their flexibility with regard to selecting hardware, software, and providers. Open RAN solutions may help minimize the reliance on highly-integrated hardware stacks once the requirement for compatibility is satisfied on a commercial level. Cloud-native core and virtualized RAN solutions will also allow greater flexibility with regard to resource planning and management. However, the shift will not render purpose-designed solutions obsolete because performance, power efficiency, and cost-effectiveness are essential factors in the industry. It seems logical that operators will adopt hybrid solutions that include both traditional RAN and virtualized solutions. Eventually, better test frameworks, standards for interfaces, and mature partnerships in the ecosystem will enhance the level of interoperability and create new opportunities for niche vendors and system integrators.
Wireless Infrastructure Market Opportunities
Private Wireless Networks for Industrial and Critical Infrastructure
Private wireless is a technology that provides the chance to expand connectivity to operational environments where regular public networks might not deliver the necessary level of control and network attributes. Private wireless networks will enable manufacturers, utilities, ports, mines, airports, and logistics companies to connect machines, sensors, personnel, autonomous vehicles, and control systems. The business case for private wireless goes beyond equipment procurement since clients need to be offered planning, spectrum management, integration, cybersecurity, device management, and optimization. Companies can develop distinctive solutions by bundling RAN, mobile core, edge computing, and managed services according to particular production processes. Cooperation with automation solution providers and system integrators can drive adoption of this solution as well as reduce the level of deployment complexity.
Network Automation and Energy Optimization Services
Network operators face growing complexity as multiple generations, spectrum bands, vendors, and deployment models coexist. This creates an opportunity for software and services that automate configuration, optimization, fault management, energy control, and predictive maintenance. AI-based orchestration can help operators identify underutilized resources and dynamically adjust network behavior according to traffic conditions. Vendors can monetize these capabilities through recurring software subscriptions, managed services, and performance-based contracts rather than relying solely on hardware cycles. Energy optimization is particularly attractive because reductions in electricity consumption can provide measurable financial benefits while supporting sustainability objectives. The opportunity also extends to multi-vendor environments where operators need centralized visibility across RAN, core, and transport assets. As network architectures become more distributed, automation can become a fundamental operational requirement rather than an optional enhancement.
Frequently Asked Questions

- Comprehensive Market Sizing and Forecast Analysis
- Detailed Segmentation Analysis
- In-Depth Market Dynamics Assessment
- Regional and Country-Level Insights
- Competitive Landscape and Company Benchmarking
- Strategic Business Intelligence
Recent Reports
Testimonials

The Insight Partners provided valuable market intelligence that supported our global go-to-market strategy. Their team was professional, responsive, and attentive to our feedback, providing thoughtful analysis and helpful methodological clarifications throughout the project.
Junmo Kim Chief Financial Officer (CFO), Enertech Co., Ltd.
The Insight Partners' SCADA System Market report is comprehensive, with valuable insights on current trends and future forecasts. The team was highly professional, responsive, and supportive throughout. We are very satisfied and highly recommend their services.
RAN KEDEM Partner, Reali Technologies LTDs
I requested a report on a very specific software market and the team produced the report in a few days. The information was very relevant and well presented. I then requested some changes and additions to the report. The team was again very responsive and I got the final report in less than a week.
JEAN-HERVE JENN Chairman, Future Analytica
We worked with The Insight Partners for an important market study and forecast. They gave us clear insights into opportunities and risks, which helped shape our plans. Their research was easy to use and based on solid data. It helped us make smart, confident decisions. We highly recommend them.
PIYUSH NAGPAL Sr. Vice President, High Beam Global
The Insight Partners delivered insightful, well-structured market research with strong domain expertise. Their team was professional and responsive throughout. The user-friendly website made accessing industry reports seamless. We highly recommend them for reliable, high-quality research services
YUKIHIKO ADACHI CEO, Deep Blue, LLC.
This is the first time I have purchased a market report from The Insight Partners.While I was unsure at first, I visited their web site and felt more comfortable to take the risk and purchase a market report.I am completely satisfied with the quality of the report and customer service. I had several questions and comments with the initial report, but after a couple of dialogs over email with their analyst I believe I have a report that I can use as input to our strategic planning process.Thank you so much for taking the extra time and making this a positive experience.I will definitely recommend your service to others and you will be my first call when we need further market data.
JOHN SUZUKI President and Chief Executive Officer, Board Director, BK Technologies
I wish to appreciate your support and the professionalism you displayed in the course of attending to my request for information regarding to infectious disease IVD market in Nigeria. I appreciate your patience, your guidance, and the fact that you were willing to offer a discount, which eventually made it possible for us to close a deal. I look forward to engaging The Insight Partners in the future, all thanks to the impression you have created in me as a result of this first encounter.
DR CHIJIOKE ONYIA MANAGING DIRECTOR, PineCrest Healthcare Ltd.Reason to Buy
- Informed Decision-Making
- Understanding Market Dynamics
- Competitive Analysis
- Identifying Emerging Markets
- Customer Insights
- Market Forecasts
- Risk Mitigation
- Boosting Operational Efficiency
- Strategic Planning
- Investment Justification
- Tracking Industry Innovations
- Aligning with Regulatory Trends





 Get Free Sample for